Corporate credit: A compelling case for investing now
Insight
November 18, 2026
If you have any feedback on this article or are interested in subscribing to our content, please contact us at opinions@muzinich.com or fill out the form on the right hand side of this page.
--------
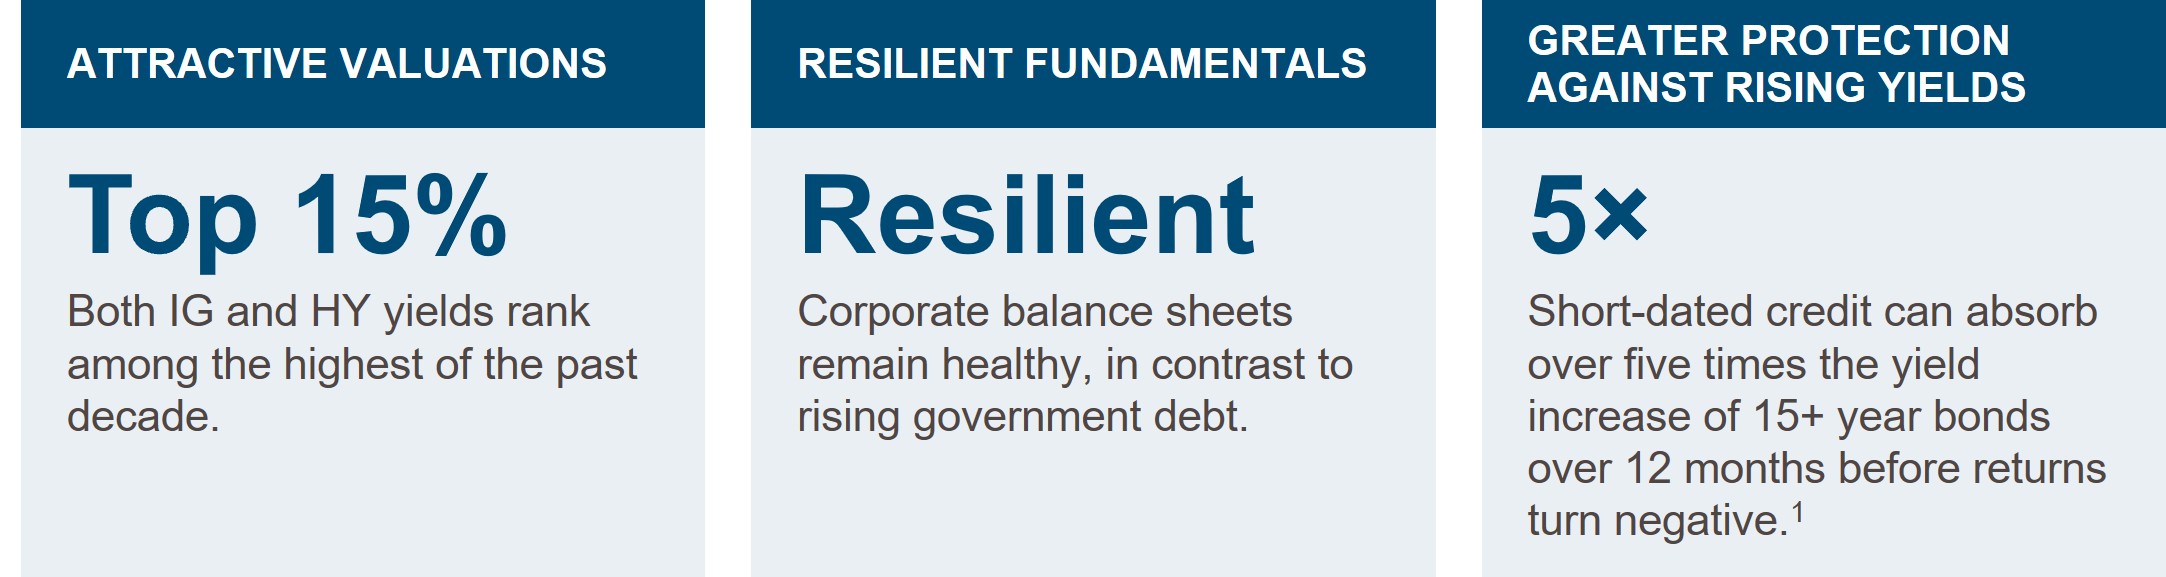
Corporate credit offers what we believe could be its best buying opportunity since 2023. With yields near the top of their 10-year ranges and resilient corporate fundamentals, investors have the potential to earn attractive returns without relying on further spread tightening or favourable market conditions. Short-duration credit looks particularly compelling.
Valuations: attractive income across credit markets
Yields across US and European investment grade (IG) and high yield (HY) are near the upper end of their 10-year historical ranges (Figure 1), providing an attractive starting point for potential returns.
Certain areas offer particularly compelling relative value. Spreads in short-dated IG and European HY are wider than their historical norms, with short-dated IG looking more attractive than longer maturities and European HY offering better value than its US counterpart.
Figure 1: Corporate credit yields have reached exceptional levels from an historical perspective
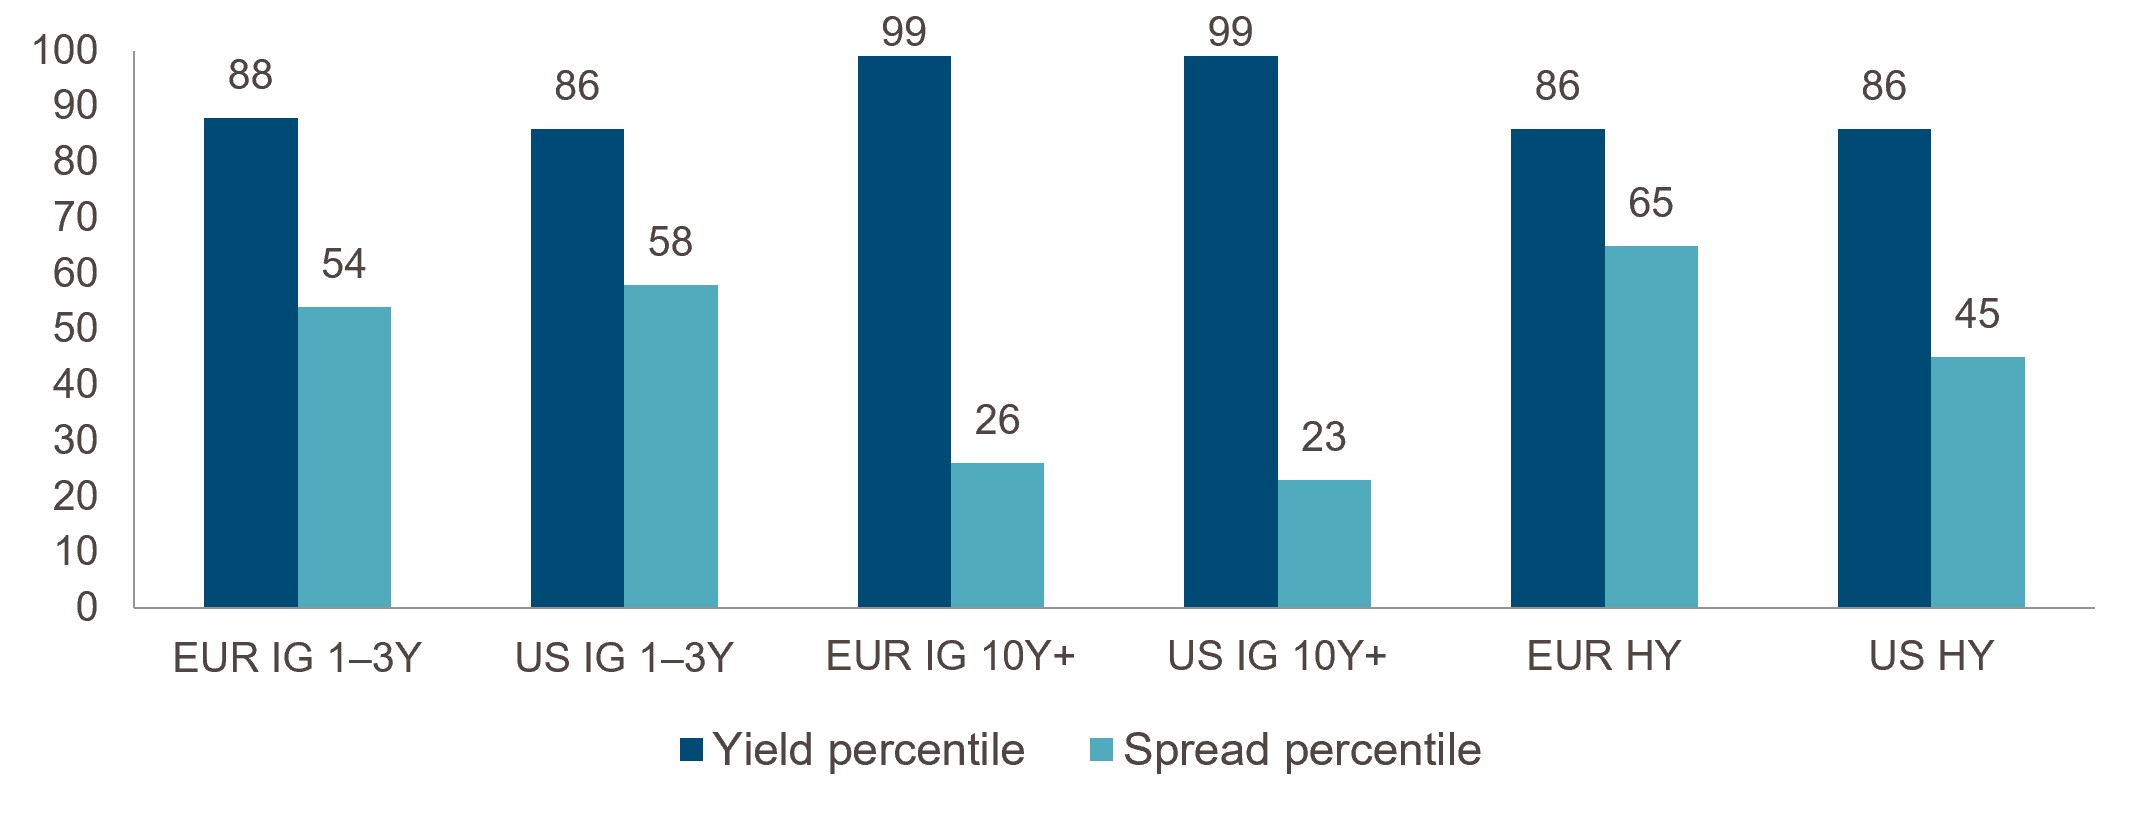 Figure 1: Source: Bloomberg and ICE Index Platform, as of 31st October 2026. Indices: EUR IG 1–3Y – I02553EU; US IG 1–3Y – LF99TRUU; EUR IG 10Y+ – I02557EU; US IG 10Y+ – I13284US; EUR HY – LP01TREU; US HY – LF98TRUU Percentiles refer to the 10-year historical distribution of each index; the 50th percentile is the median. For illustrative purposes only
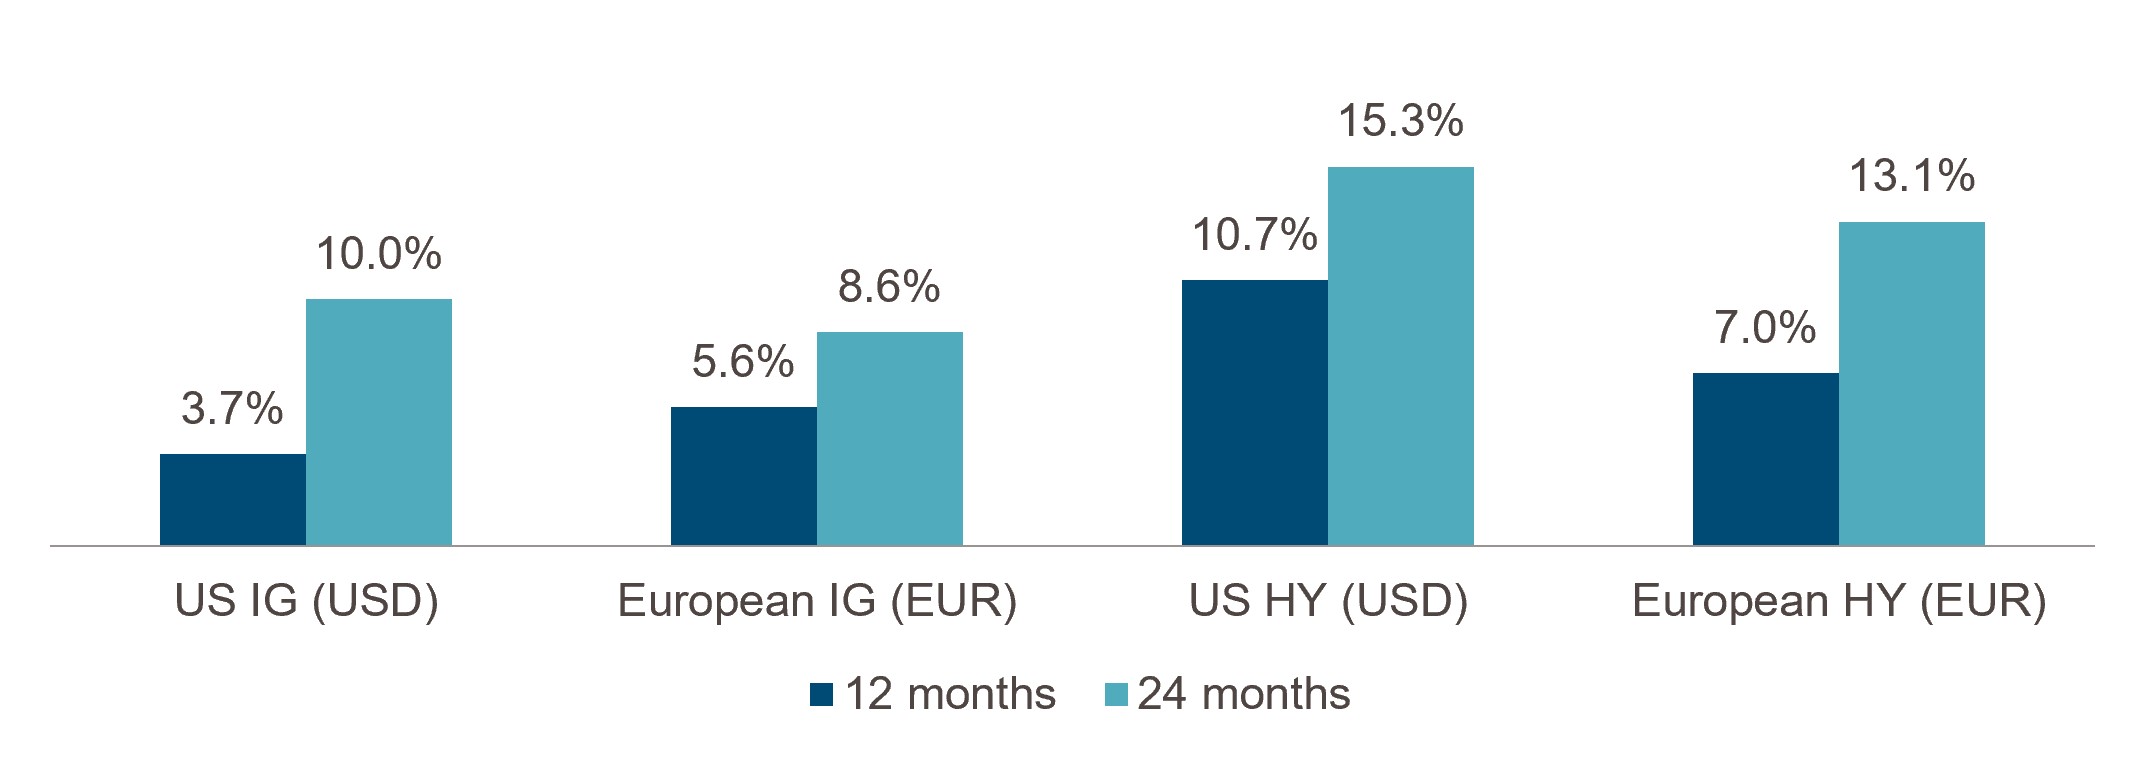
For investors who missed the strong returns following the buying opportunity in 2023, today's market may offer a second chance. Historically, starting yields comparable to current levels have been associated with attractive subsequent returns. Figure 2 shows the average returns achieved across European and US credit markets over the following 12 and 24 months when yields were at similar levels.
Figure 2: Similar starting yields have historically delivered strong returns
Past performance is not a reliable indicator of current or future results.
Fundamentals: corporate resilience against a challenging sovereign backdrop
Higher yields do not necessarily mean weaker corporate credit quality. Economic growth remains resilient, while healthy earnings and disciplined balance sheets continue to underpin corporate fundamentals.
The contrast with sovereign borrowers is increasingly stark. While companies have generally kept leverage in check (Fig. 3) and maintained disciplined cash-flow management, governments face mounting debt burdens (Fig. 4), persistent fiscal deficits and rising borrowing costs.
For credit investors, this distinction matters. Corporate earnings, cash flows and debt-servicing capacity offer greater visibility into financial risk, supporting more informed investment decisions.
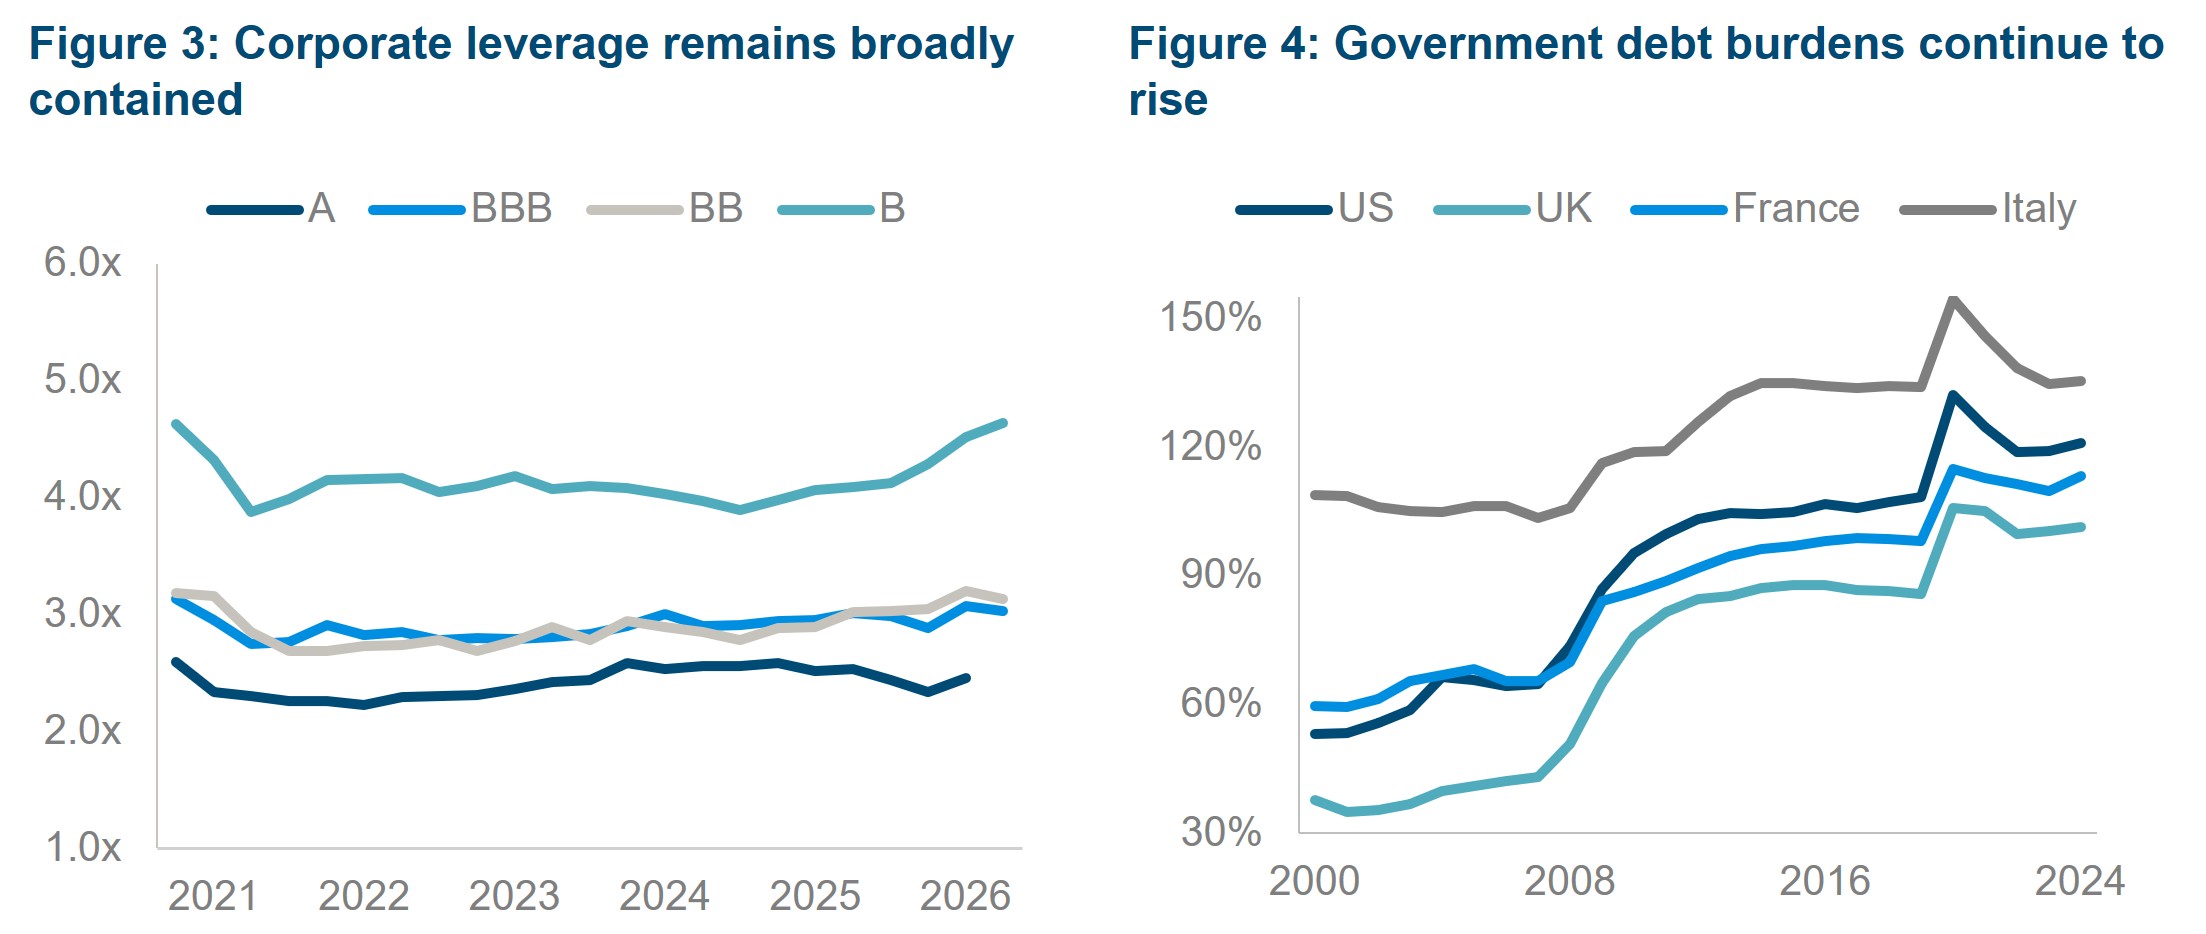
Figure 2: Source: ICE Index Platform, as of 9th November 2026. Average cumulative index total returns following daily starting yields in the current 50bp band. Returns are cumulative, not annualised; overlapping periods are not independent. USIG – C0A0, European IG – ER00, USHY – H0A0, EURHY – HE00. Data from 3rd January 2000. For illustrative purposes only.
Figure 3: Source: Bloomberg Intelligence. Net debt to EBITDA by rating, quarterly, as of 30th June 2026. For illustrative purposes only.
Figure 4: Source: IMF Global Debt Database, via Bloomberg. General government gross debt as % of GDP, annual (year-end) as of 31st December 2024. Latest available data used. For illustrative purposes only.
Income as a first line of defence
Attractive starting yields provide a cushion against market volatility, helping protect returns if interest rates rise or credit spreads widen. This protection is particularly strong in short-duration credit, where bond prices are less sensitive to changes in yields.
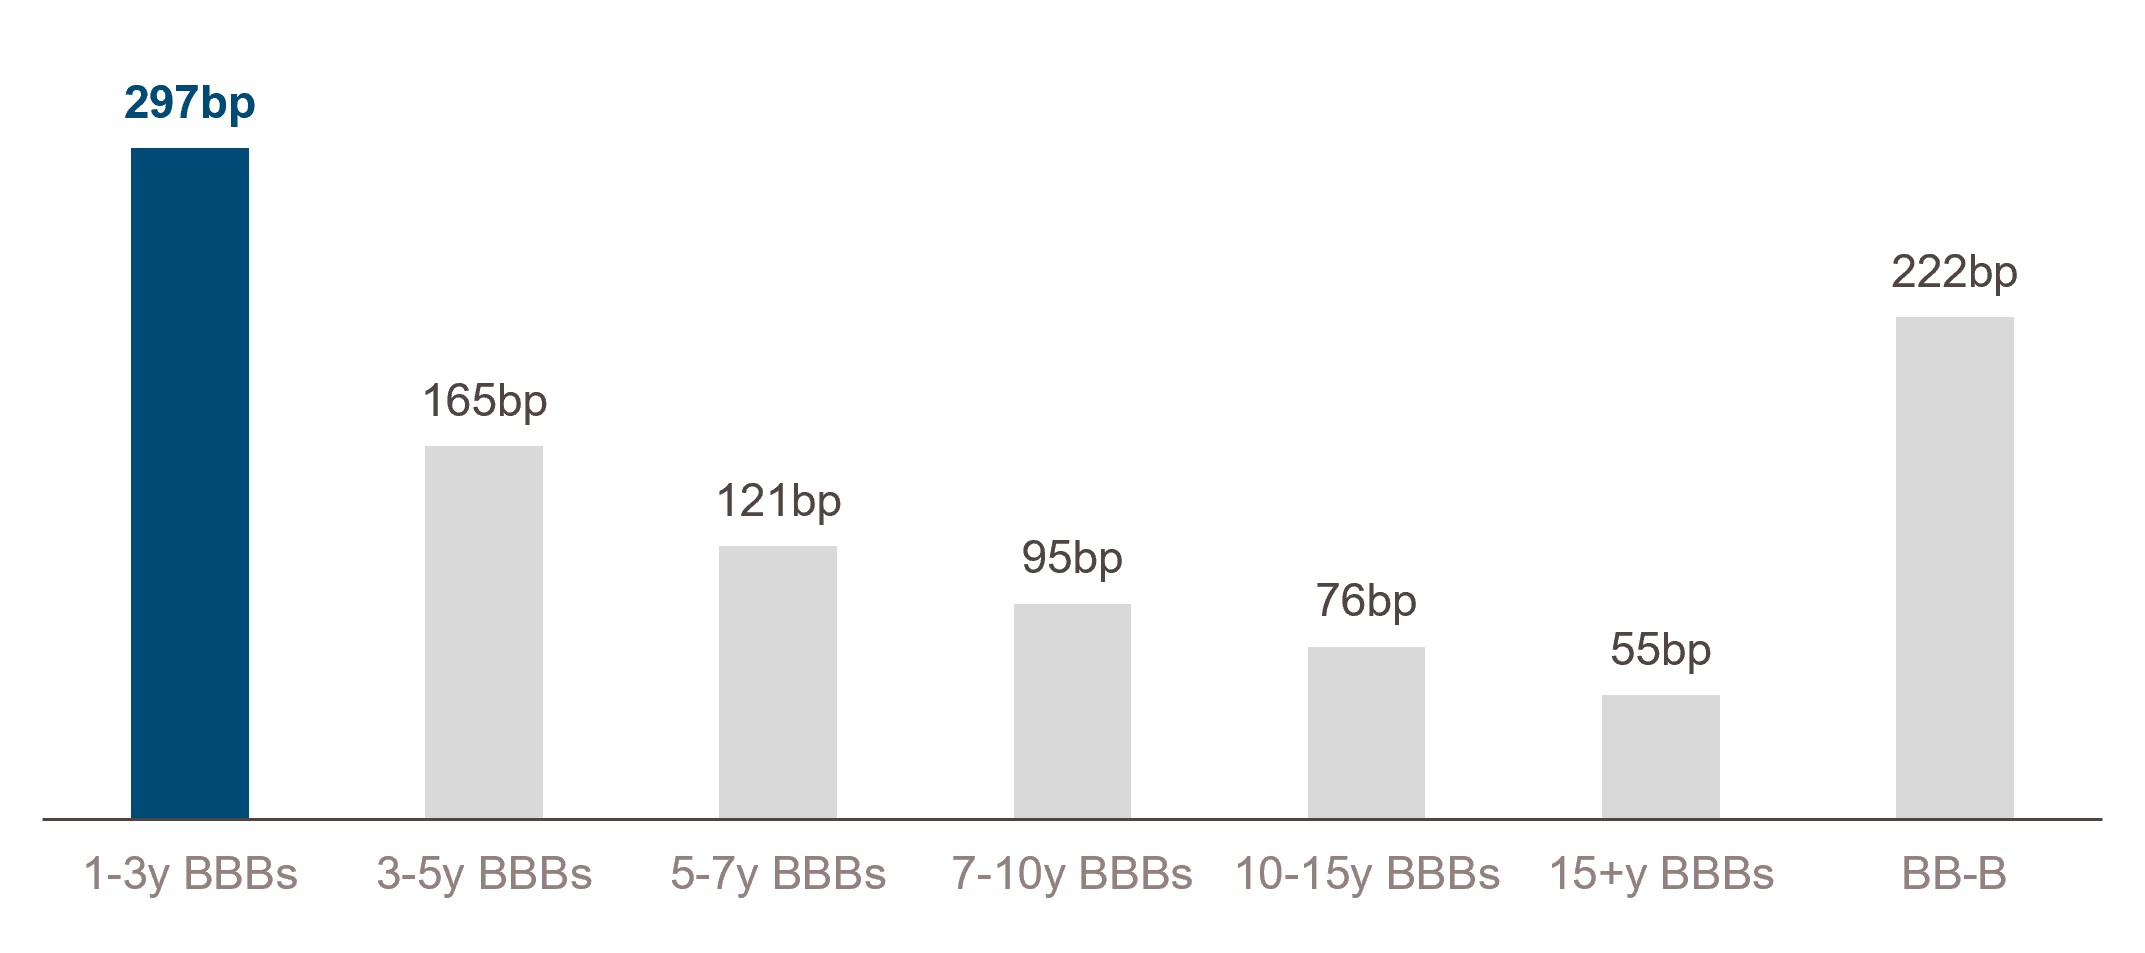
A simple way to measure this cushion is through breakeven, calculated by dividing yield by duration. Figure 5 shows how much yields could rise over 12 months before the income earned is offset by capital losses, highlighting the downside protection offered by short-duration IG.
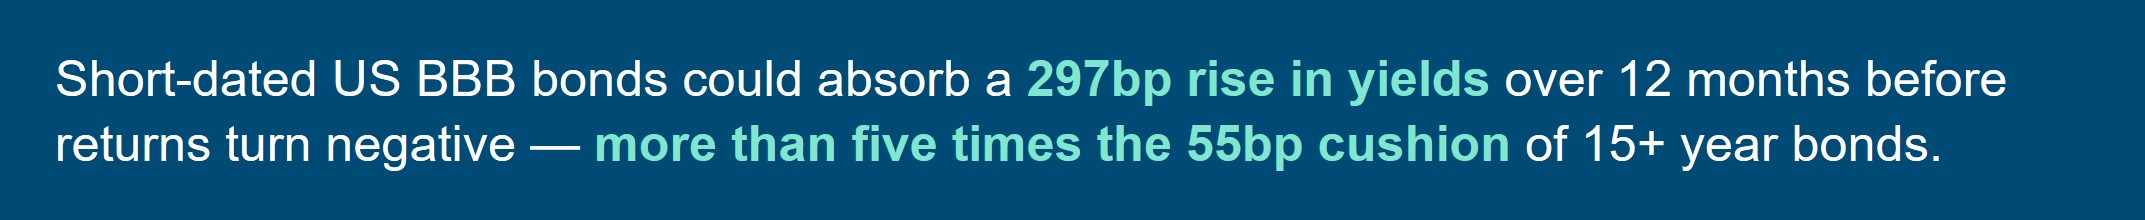
Figure 5: Short-dated credit offers over 5× the yield-rise cushion
USD BBBs – 12-month total return breakevens
EUR BBBs – 12-month total return breakevens (USD hedged)
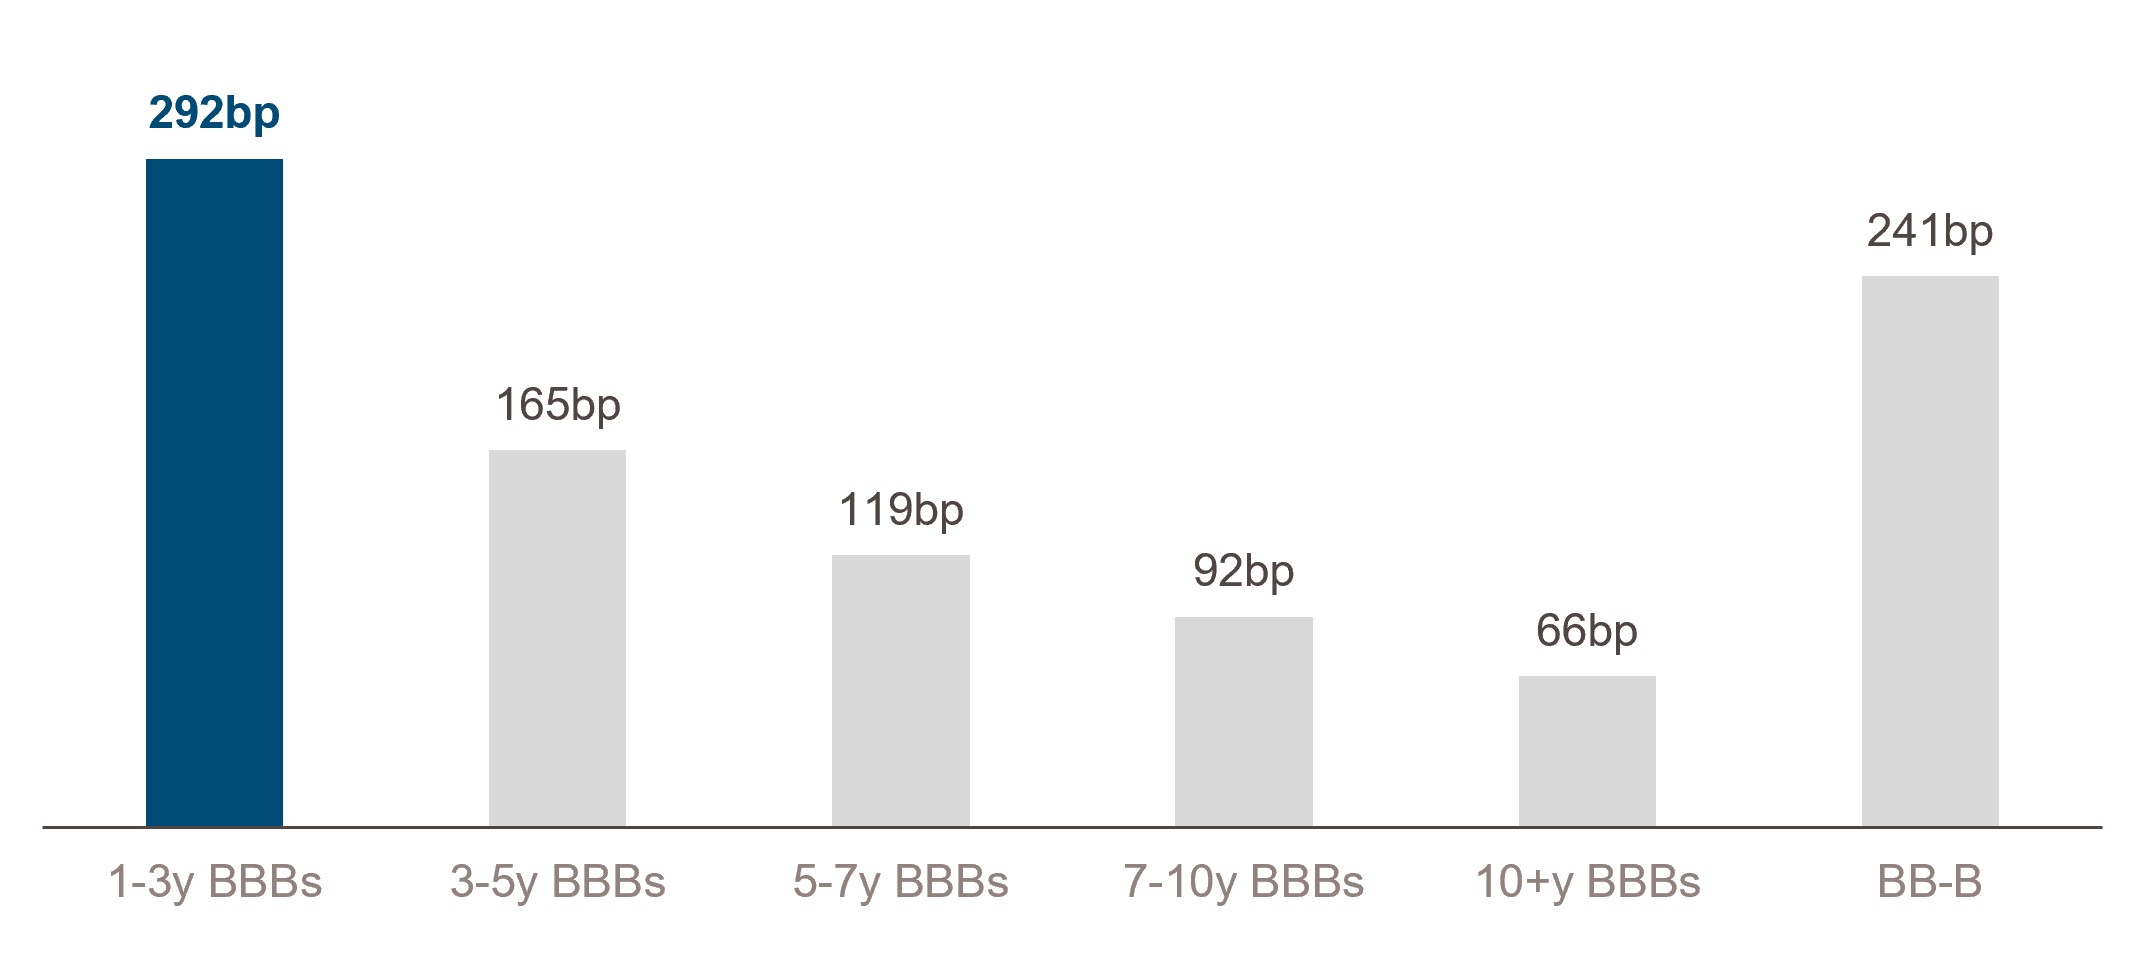
Figure 5: Source: Muzinich, Bloomberg and ICE Data Platform, as of October 31st 2026. C1A4, C2A4, C3A4, C4A4, C7A4, C8A4, ER41, ER42, ER43, ER44, ER49, J0A4, HE40 and FXHCEUUS Index. Indices selected by Muzinich as best available proxies for their respective markets. For illustrative purposes only.
Historical risk-adjusted returns also support the case for shorter-duration credit. Short-dated IG and HY indices have historically delivered stronger risk-adjusted returns than their broader market counterparts, generating more return relative to the volatility experienced (Figure 6).
Figure 6: Short-duration credit has delivered stronger risk-adjusted returns
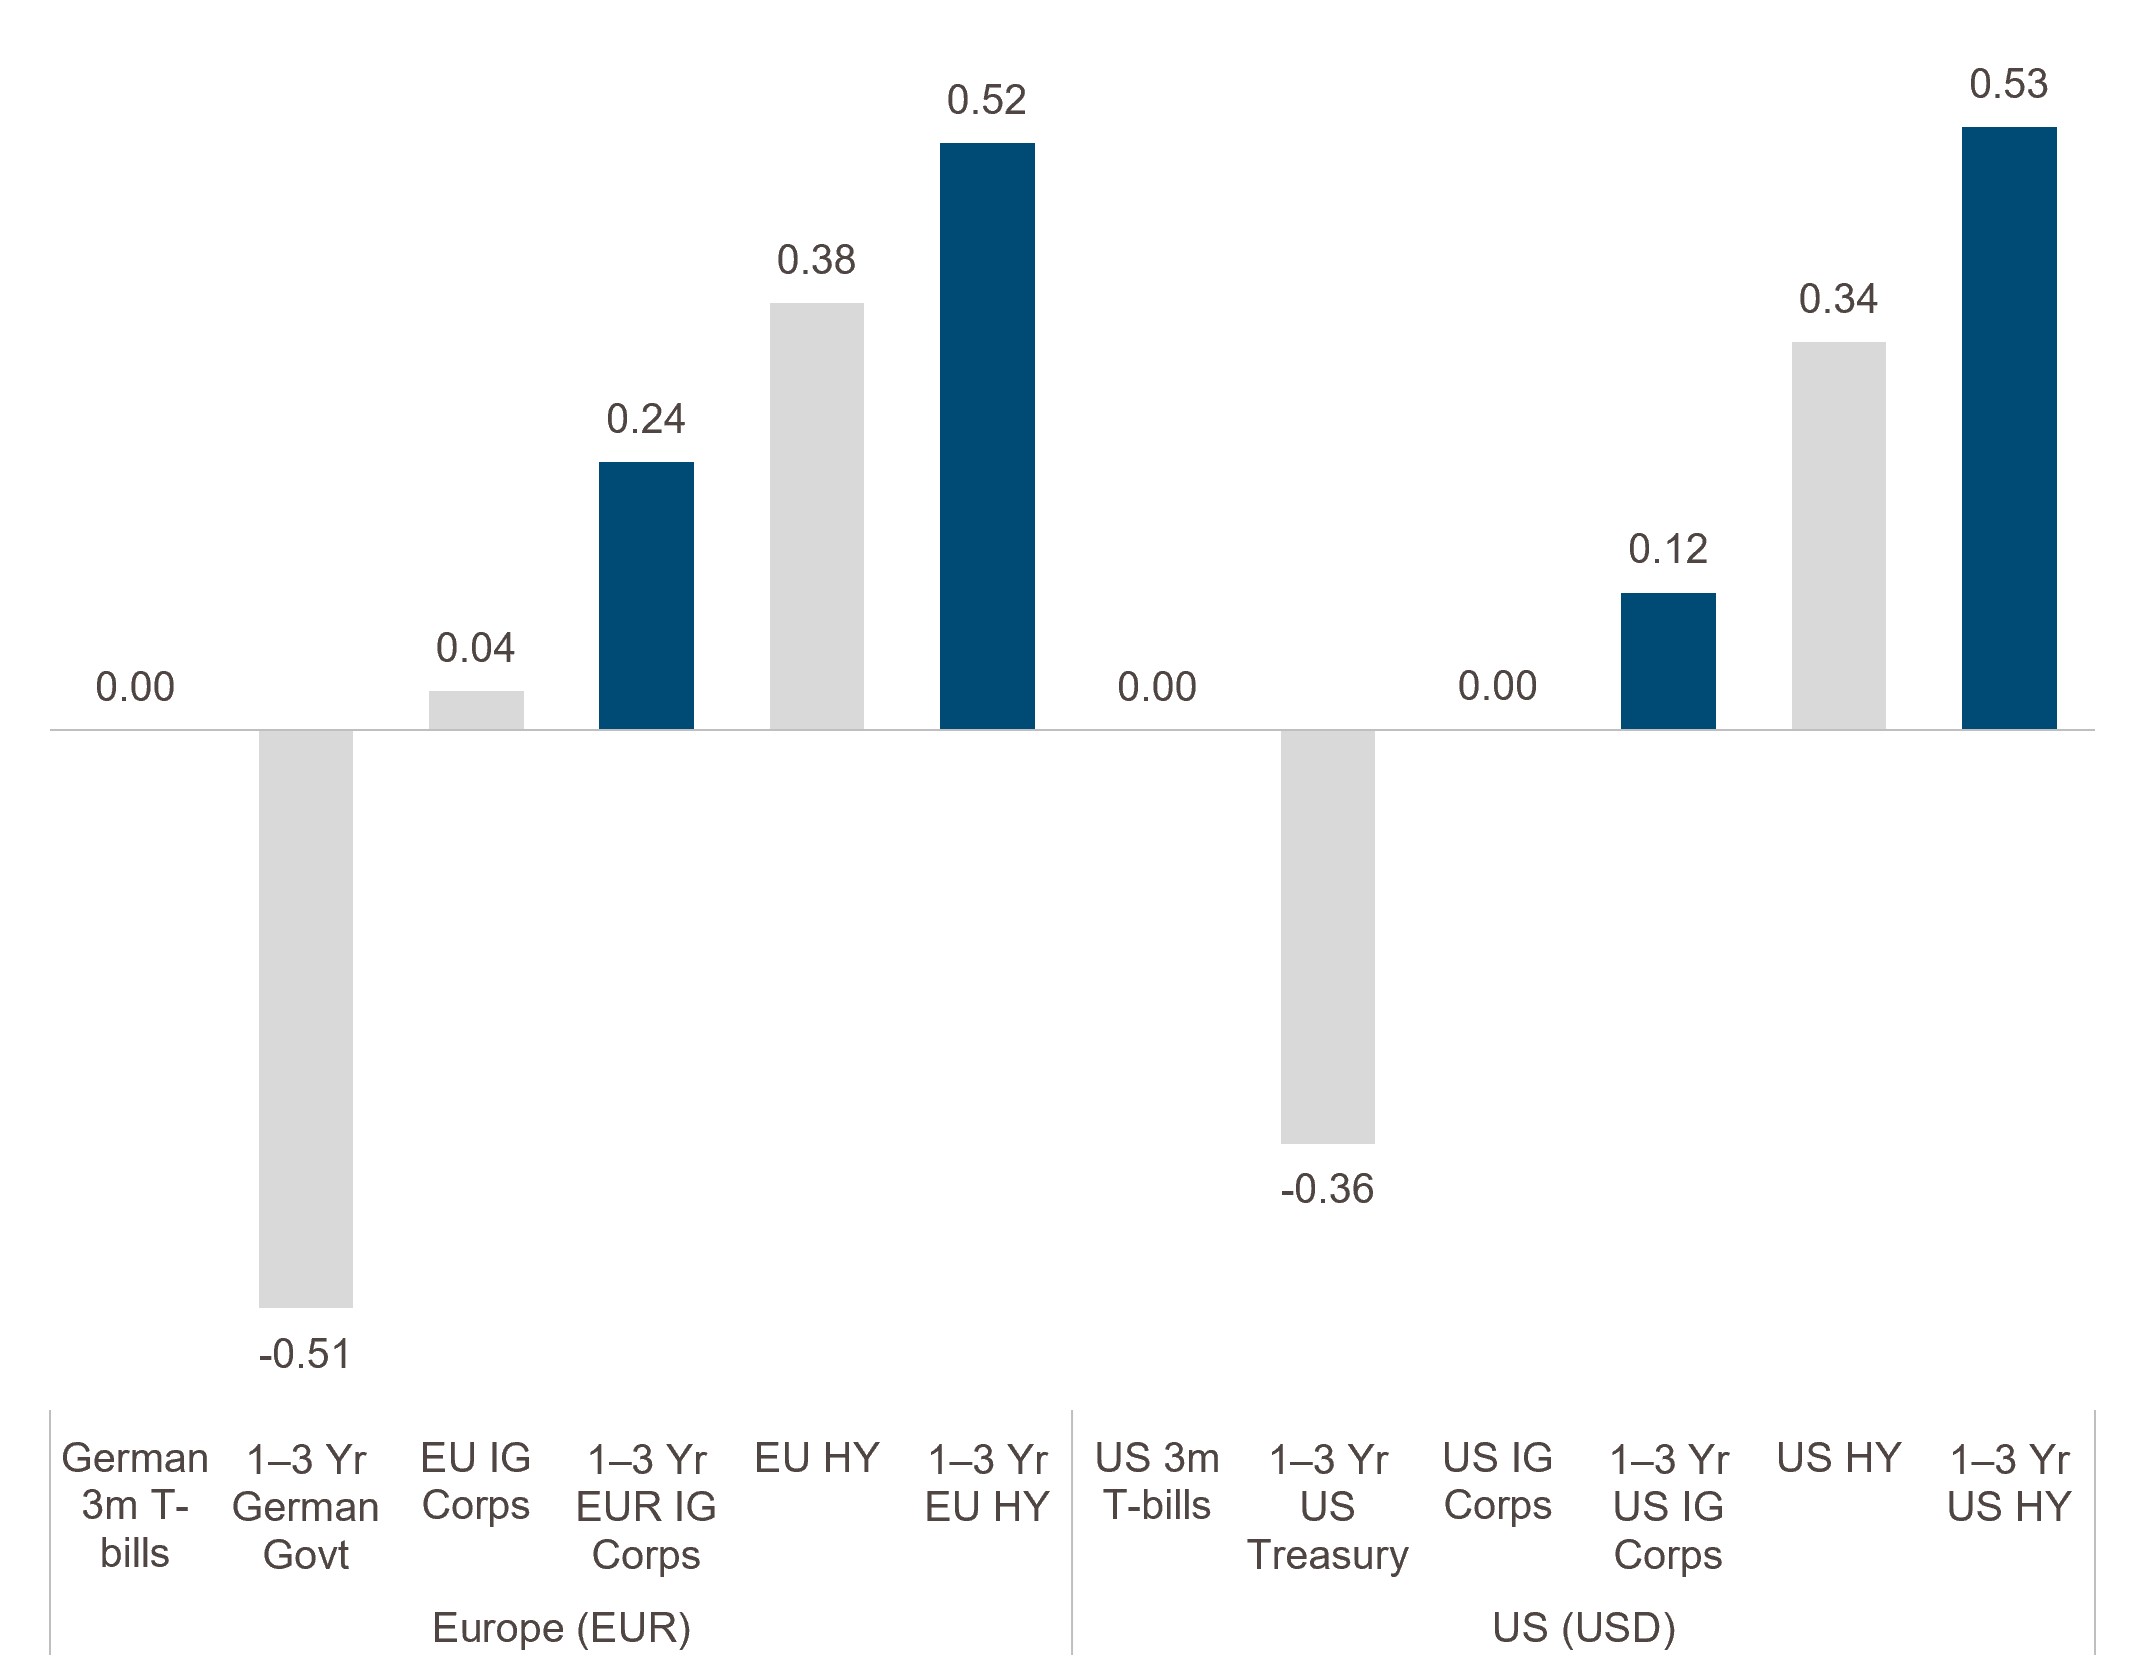
Figure 6: Source: ICE Index Platform as of October 31st, 2026. ER01, ER21, ER31, ER41, HE00, HE10, HE20, G1D0, G0DB, EMU0, EMU1, ER00, G0O1, G1O2, C0A0, C1A0, J0A4, J1A4. US HY uses BB-B indices (J0A4, J1A4). See index descriptions on slide 6 for more information. For illustrative purposes only.
Conclusion
Investors need not rely on falling interest rates or further spread tightening to find opportunities in corporate credit. With yields historically elevated and corporate fundamentals resilient, we believe selective short-duration IG and HY offer a compelling combination of income, return potential and resilience to market volatility.
This material is not intended to be relied upon as a forecast, research, or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or to adopt any investment strategy. The opinions expressed by Muzinich & Co. are as of November 2026 and may change without notice.
--------
Index descriptions
ER01 – The ICE BofA 1-3 Year Euro Corporate Index is a subset of ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to maturity less than 3 years.
ER21 – The ICE BofA 1-3 Year AA Euro Corporate Index is a subset of the ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to final maturity less than 3 years and rated AA1 through AA3, inclusive.
ER31 – The ICE BofA 1-3 Year Single-A Euro Corporate Index is a subset of ICE BofA Euro Corporate Index including all securities with a remaining term to final maturity less than 3 years and rated A1 through A3, inclusive.
ER41 – The ICE BofA 1-3 Year BBB Euro Corporate Index is a subset of the ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to final maturity less than 3 years and rated BBB1 through BBB3, inclusive.
HE00 – The ICE BofA Euro High Yield Index tracks the performance of EUR denominated below investment grade corporate debt publicly issued in the euro domestic or eurobond markets. Qualifying securities must have a below investment grade rating (based on an average of Moody’s, S&P and Fitch), at least 18 months to final maturity at the time of issuance, at least one year remaining term to final maturity, a fixed coupon schedule and a minimum amount outstanding of EUR 250 million.
HE10 – The ICE BofA BB Euro High Yield Index is a subset of the ICE BofA Euro High Yield Index (HE00) including all securities rated BB1 through BB3, inclusive.
HE20 – The ICE BofA Single-B Euro High Yield Index is a subset of the ICE BofA Euro High Yield Index (HE00) including all securities rated B1 through B3, inclusive.
G1D0 – The ICE BofA German Federal Government (1-3 year) Index is a subset of the ICE BofA German Government Index (G0D0) including all securities with a remaining term to final maturity greater than or equal to 1 years and less than 3 years.
G0DB – The ICE BofA German Treasury Bill Index tracks the performance of EUR denominated sovereign bills publicly issued by the German government in the German domestic or eurobond market. Qualifying securities must have at least one month and less than one year remaining term to final maturity and a minimum amount outstanding of EUR 1 billion.
EMU0 – The ICE BofA Euro Broad Market Index tracks the performance of EUR denominated investment grade debt publicly issued in the eurobond or Euro member domestic markets, including euro-sovereign, quasi-government, corporate, securitized and collateralized securities. Qualifying securities must have an investment grade rating (based on an average of Moody’s, S&P and Fitch), at least 18 months to final maturity at the time of issuance, at least one year remaining term to final maturity, a fixed coupon schedule and a minimum amount outstanding of EUR 1 billion for sovereign securities and EUR 250 million for all other securities.
EMU1 – The ICE BofA 1-3 Year Euro Broad Market Index is a subset of the ICE BofA Euro Broad Market Index (EMU0) including all securities with a remaining term to final maturity less than 3 years.
ER00 – The ICE BofA Euro Corporate Index tracks the performance of EUR denominated investment grade corporate debt publicly issued in the eurobond or Euro member domestic markets. Qualifying securities must have an investment grade rating (based on an average of Moody’s, S&P and Fitch), at least 18 months to final maturity at the time of issuance, at least one year remaining term to final maturity, a fixed coupon schedule and a minimum amount outstanding of EUR 250 million.
C0A0 – The ICE BofA US Corporate Index tracks the performance of US dollar denominated investment grade corporate debt publicly issued in the US domestic market. Qualifying securities must have an investment grade rating (based on an average of Moody’s, S&P and Fitch), at least 18 months to final maturity at the time of issuance, at least one year remaining term to final maturity as of the rebalancing date, a fixed coupon schedule and a minimum amount outstanding of $250 million.
C1A0 – ICE BofA 1-3 Year US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity less than 3 years.
C1A4 – ICE BofA 1-3 Year BBB US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity less than 3 years and rated BBB1 through BBB3, inclusive.
C2A4 – ICE BofA 3-5 Year BBB US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity greater than or equal to 3 years and less than 5 years and rated BBB1 through BBB3, inclusive.
C3A4 – ICE BofA 5-7 Year BBB US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity greater than or equal to 5 years and less than 7 years and rated BBB1 through BBB3, inclusive.
C4A4 – ICE BofA 7-10 Year BBB US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity greater than or equal to 7 years and less than 10 years and rated BBB1 through BBB3, inclusive.
C7A4 – The ICE BofA 10-15 Year BBB US Corporate Index is a subset of the ICE BofA US Corporate Index (C0A0) including all securities with a remaining term to final maturity greater than or equal to 10 years and less than 15 years and rated BBB1 through BBB3, inclusive.
C8A4 – ICE BofA 15+ Year BBB US Corporate Index is a subset of ICE BofA US Corporate Index including all securities with a remaining term to final maturity greater than or equal to 15 years and rated BBB1 through BBB3, inclusive.
ER42 – ICE BofA 3-5 Year BBB Euro Corporate Index is a subset of ICE BofA Euro Corporate Index including all securities with a remaining term to final maturity greater than or equal to 3 years and less than 5 years and rated BBB1 through BBB3, inclusive.
ER43 – The ICE BofA 5-7 Year BBB Euro Corporate Index is a subset of the ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to final maturity greater than or equal to 5 years and less than 7 years and rated BBB1 through BBB3, inclusive.
ER44 – The ICE BofA 7-10 Year BBB Euro Corporate Index is a subset of the ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to final maturity greater than or equal to 7 years and less than 10 years and rated BBB1 through BBB3, inclusive.
ER49 – The ICE BofA 10+ Year BBB Euro Corporate Index is a subset of the ICE BofA Euro Corporate Index (ER00) including all securities with a remaining term to final maturity greater than or equal to 10 years and rated BBB1 through BBB3, inclusive.
J0A4 – The ICE BofA BB-B US Cash Pay High Yield Index is a subset of the ICE BofA US Cash Pay High Yield Index (J0A0) including all securities rated BB1 through B3, inclusive.
J1A4 – The ICE BofA 1-3 Year BB-B US Cash Pay High Yield Index is a subset of the ICE BofA US Cash Pay High Yield Index (J0A0) including all securities with a remaining term to final maturity less than 3 years and rated BB1 through B3, inclusive.
HE40 – ICE BofA BB-B Euro High Yield Index is a subset of ICE BofA Euro High Yield Index including all securities rated BB1 through B3, inclusive.
FXHCEUUS Index – Bloomberg EURUSD 3 Month Hedging Cost shows the three-month euro hedge cost for dollar-based investors on an annualised basis. This is based on the assumption the investors sell dollars to buy euros in the spot market and simultaneously sell euros in the forward market to buy back dollars.
--------
Important information
Muzinich and/or Muzinich & Co. referenced herein is defined as Muzinich & Co., Inc. and its affiliates. Muzinich views and opinions. This material has been produced for information purposes only and as such the views contained herein are not to be taken as investment advice. Opinions are as of date of publication and are subject to change without reference or notification to you. Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy. The value of investments and the income from them may fall as well as rise and is not guaranteed and investors may not get back the full amount invested. Rates of exchange may cause the value of investments to rise or fall.
Any research in this document has been obtained and may have been acted on by Muzinich for its own purpose. The results of such research are being made available for information purposes and no assurances are made as to their accuracy. Opinions and statements of financial market trends that are based on market conditions constitute our judgment and this judgment may prove to be wrong. The views and opinions expressed should not be construed as an offer to buy or sell or invitation to engage in any investment activity, they are for information purposes only.
This discussion material contains forward-looking statements, which give current expectations of future activities and future performance. Any or all forward-looking statements in this material may turn out to be incorrect. They can be affected by inaccurate assumptions or by known or unknown risks and uncertainties. Although the assumptions underlying the forward-looking statements contained herein are believed to be reasonable, any of the assumptions could be inaccurate and, therefore, there can be no assurances that the forward-looking statements included in this discussion material will prove to be accurate. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation that the objectives and plans discussed herein will be achieved. Further, no person undertakes any obligation to revise such forward-looking statements to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events.
United Arab Emirates (UAE): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the UAE. It is intended solely for Professional Investors and should not be relied upon by any other person. This material has not been reviewed or approved by the UAE Securities and Commodities Authority, the UAE Central Bank or any other relevant authority. Nothing contained herein constitutes investment, legal, tax or other professional advice. Recipients should make their own independent assessment where appropriate.
Abu Dhabi Global Market (ADGM): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the ADGM. It is intended solely for Professional Clients (as defined by the Financial Services Regulatory Authority) and should not be relied upon by any other person. This material has not been reviewed or approved by the Financial Services Regulatory Authority or any other relevant authority in the UAE.
DIFC: This material is intended solely for Professional Clients as defined by the Rules of the Dubai Financial Services Authority ("DFSA") and must not be delivered to, or relied upon by, any other person, including Retail Clients. It is provided for information and discussion purposes only and does not constitute an offer, solicitation, recommendation or investment advice, nor should it be construed as such.
Where this material relates to a fund or investment product, it may not be suitable for all investors and prospective investors should conduct their own due diligence and seek independent professional advice prior to making any investment decision. Where this material is distributed by a firm authorised and regulated by the DFSA, it is communicated in accordance with applicable DFSA rules.
United States: This material is for Institutional Investor use only – not for retail distribution. Muzinich & Co., Inc. is a registered investment adviser with the Securities and Exchange Commission (SEC). Muzinich & Co., Inc.’s being a Registered Investment Adviser with the SEC in no way shall imply a certain level of skill or training or any authorization or approval by the SEC.
Issued in the European Union by Muzinich & Co. (Ireland) Limited, which is authorized and regulated by the Central Bank of Ireland. Registered in Ireland, Company Registration No. 307511. Registered address: 32 Molesworth Street, Dublin 2, D02 Y512, Ireland. Issued in Switzerland by Muzinich & Co. (Switzerland) AG. Registered in Switzerland No. CHE-389.422.108. Registered address: Tödistrasse 5, 8002 Zurich, Switzerland. Issued in Singapore and Hong Kong by Muzinich & Co. (Singapore) Pte. Limited, which is licensed and regulated by the Monetary Authority of Singapore. Registered in Singapore No. 201624477K. Registered address: 6 Battery Road, #26-05, Singapore, 049909. Issued in all other jurisdictions (excluding the U.S.) by Muzinich & Co. Limited. which is authorized and regulated by the Financial Conduct Authority. Registered in England and Wales No. 3852444. Registered address: 8 Hanover Street, London W1S 1YQ, United Kingdom. 2026-11-17-19882
By clicking "Submit", I am (i) signing up to receive the Opinion Pieces from the "Opinions" page of the Muzinich & Co website, (ii) representing that the above information is true and accurate and (iii) agreeing to join the Muzinich & Co mailing list. I understand that Muzinich & Co will not add retail investors or individuals with personal email addresses to its mailing list and represent that I am not a retail investor. By providing my personal and professional information I am consenting to its use and disclosure in accordance with the Muzinich & Co. Privacy Policy. I understand that I may withdraw my consent and unsubscribe from receiving future communications by clicking "Unsubscribe" from the emails that are sent to me from Muzinich & Co.
Nov 16, 2026
Muzinich Weekly Market Comment: Tempting Fate
It was a good week for risk assets, but a much tougher one for safe havens. Government bond yields rose across the world, with US Treasuries adjusting most violently.
Nov 13, 2026
Muzinich Asset Allocation Group Monthly Update - November 2026
Please click to watch our latest Asset Allocation Group video update for the month of November 2026.
Nov 09, 2026
Muzinich Weekly Market Comment: The Executive Years – Two Years, One Pen
It was a good week for healthcare and green energy, and for the Democrats. Less so for AI, fossil fuels and defence, and for the Republicans.