AI’s funding boom: What bond markets are telling us
Insight
October 6, 2026
If you have any feedback on this article or are interested in subscribing to our content, please contact us at opinions@muzinich.com or fill out the form on the right hand side of this page.
--------
The market is showing its hand. The cadence of AI-related debt issuance is increasingly influencing credit spreads, creating supply-driven risks as well as opportunities for active managers to dynamically adjust exposure as issuance ebbs and flows.
1. AI investment is driving a surge in tech debt issuance
Heavy and sometimes unexpected issuance has tested the market’s capacity to absorb supply. Since September 2025, the US investment-grade (IG) market has seen more than US$350bn in hyperscaler and datacenter-related issuance.
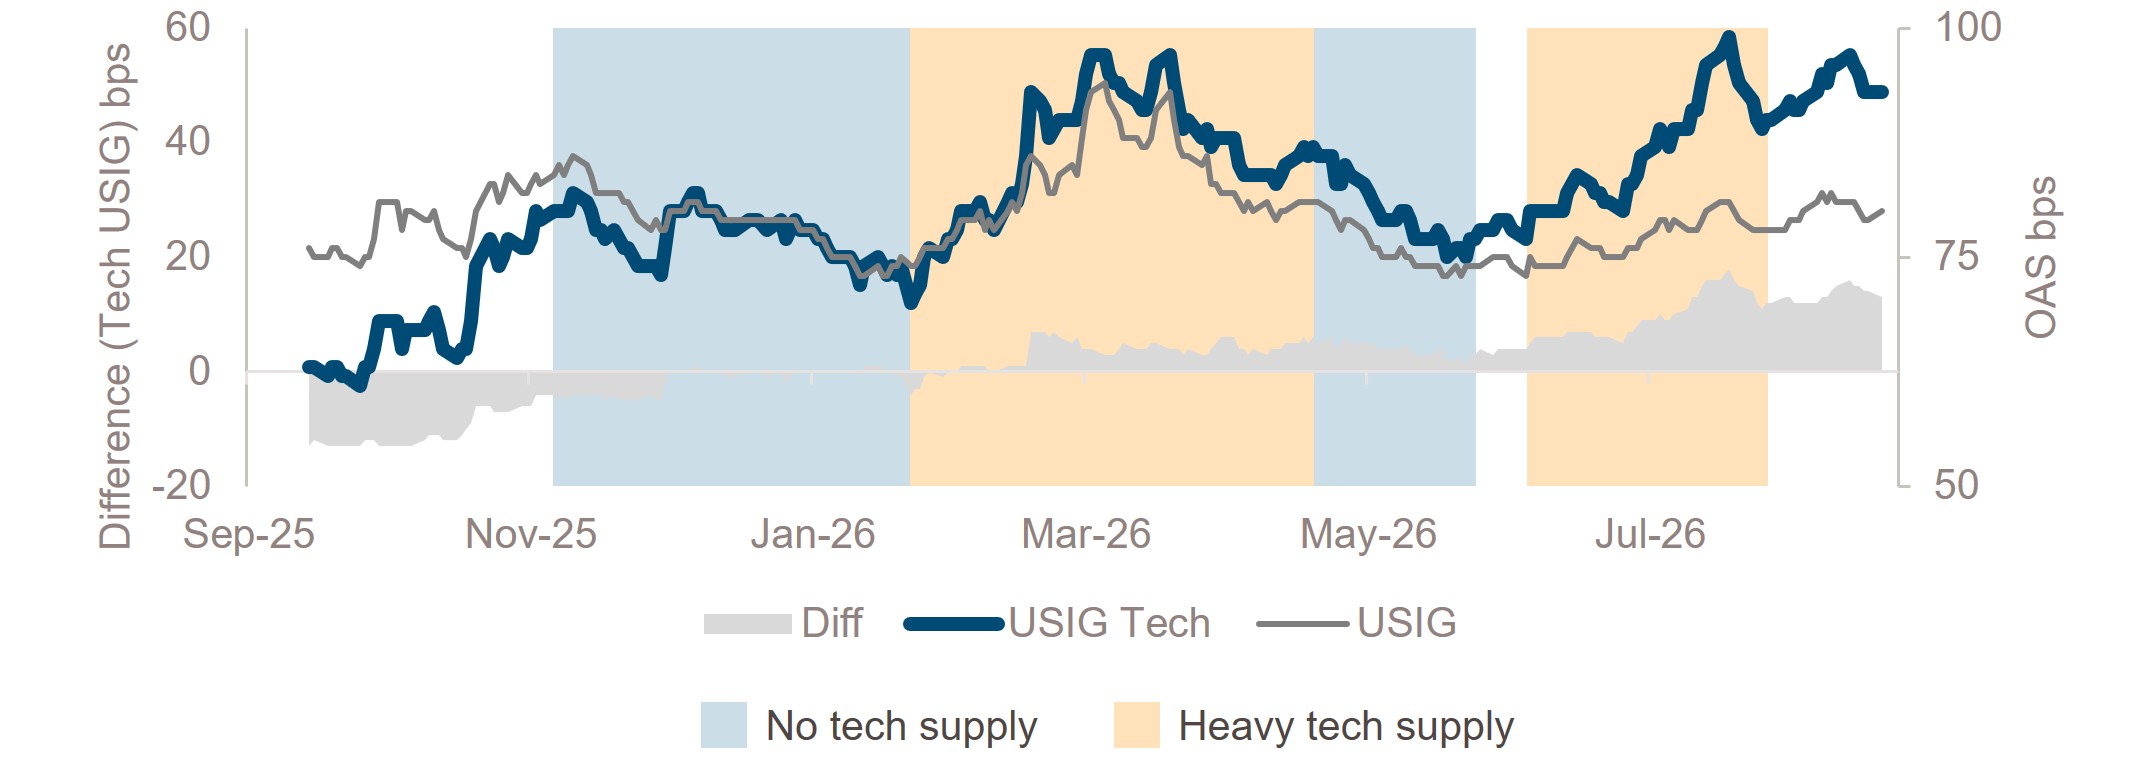
Our analysis suggests the cadence of issuance matters. Heavy technology supply has coincided with wider spreads across US IG and relative underperformance from technology, while pauses in issuance have seen spreads rally. Against this backdrop, US technology credit has repriced from around 10bps tighter than US investment grade in September 2025 to around 15bps wider today – a c.25bps relative move (Fig. 3).
Figure 1: Tech spreads have widened during heavy issuance – and rallied when supply pauses
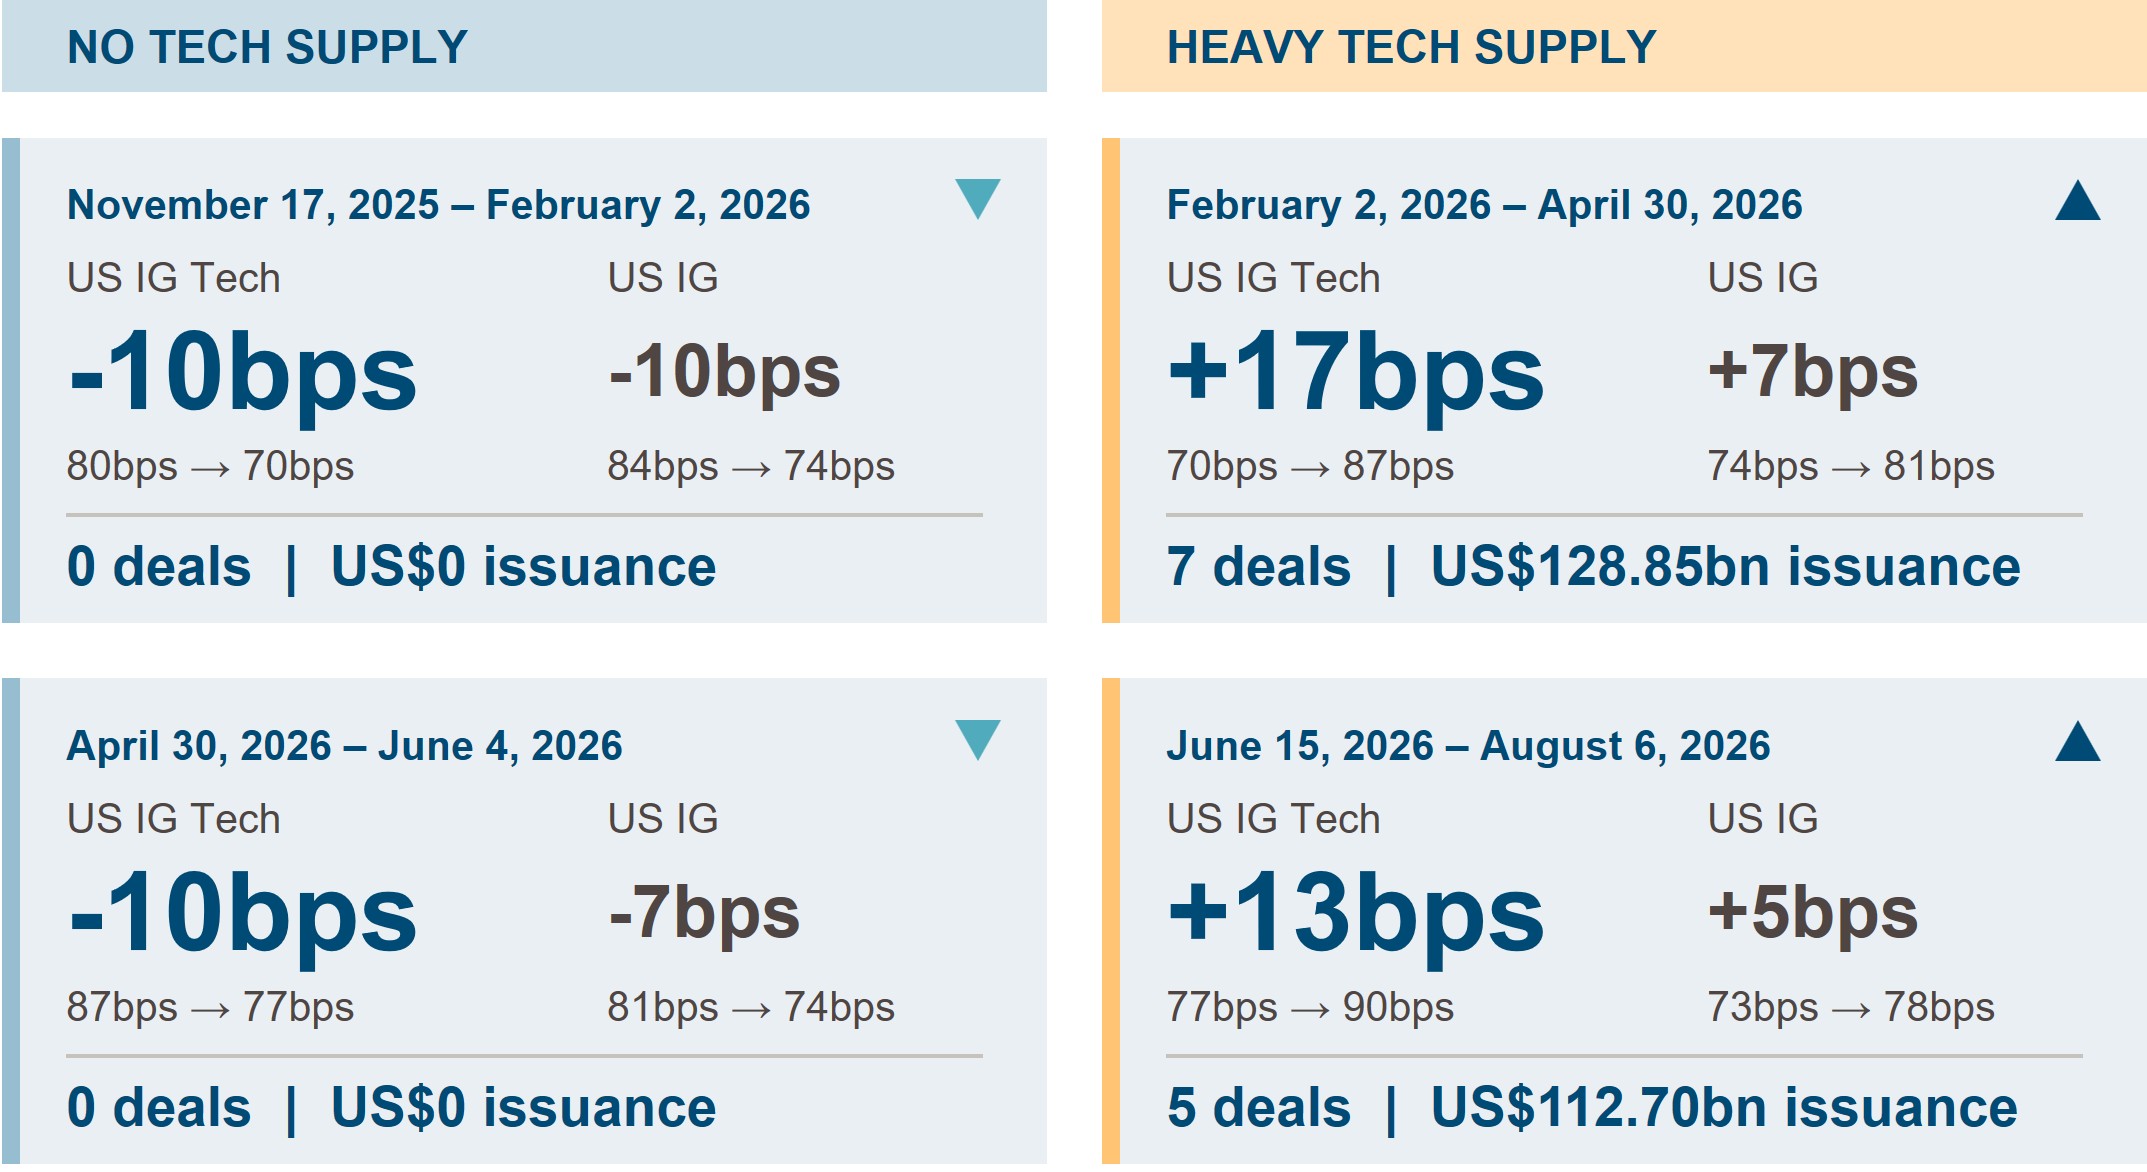
Source: ICE Index Platform, as of September 16, 2026. US IG – ICE BofA US Investment Grade Corporate Index (C0A0), ICE BofA US Technology & Electronics Index (CITE). Indices used are the best proxy for subject under discussion. For illustrative purposes only.
Figure 2: Debt issuance by announcement date
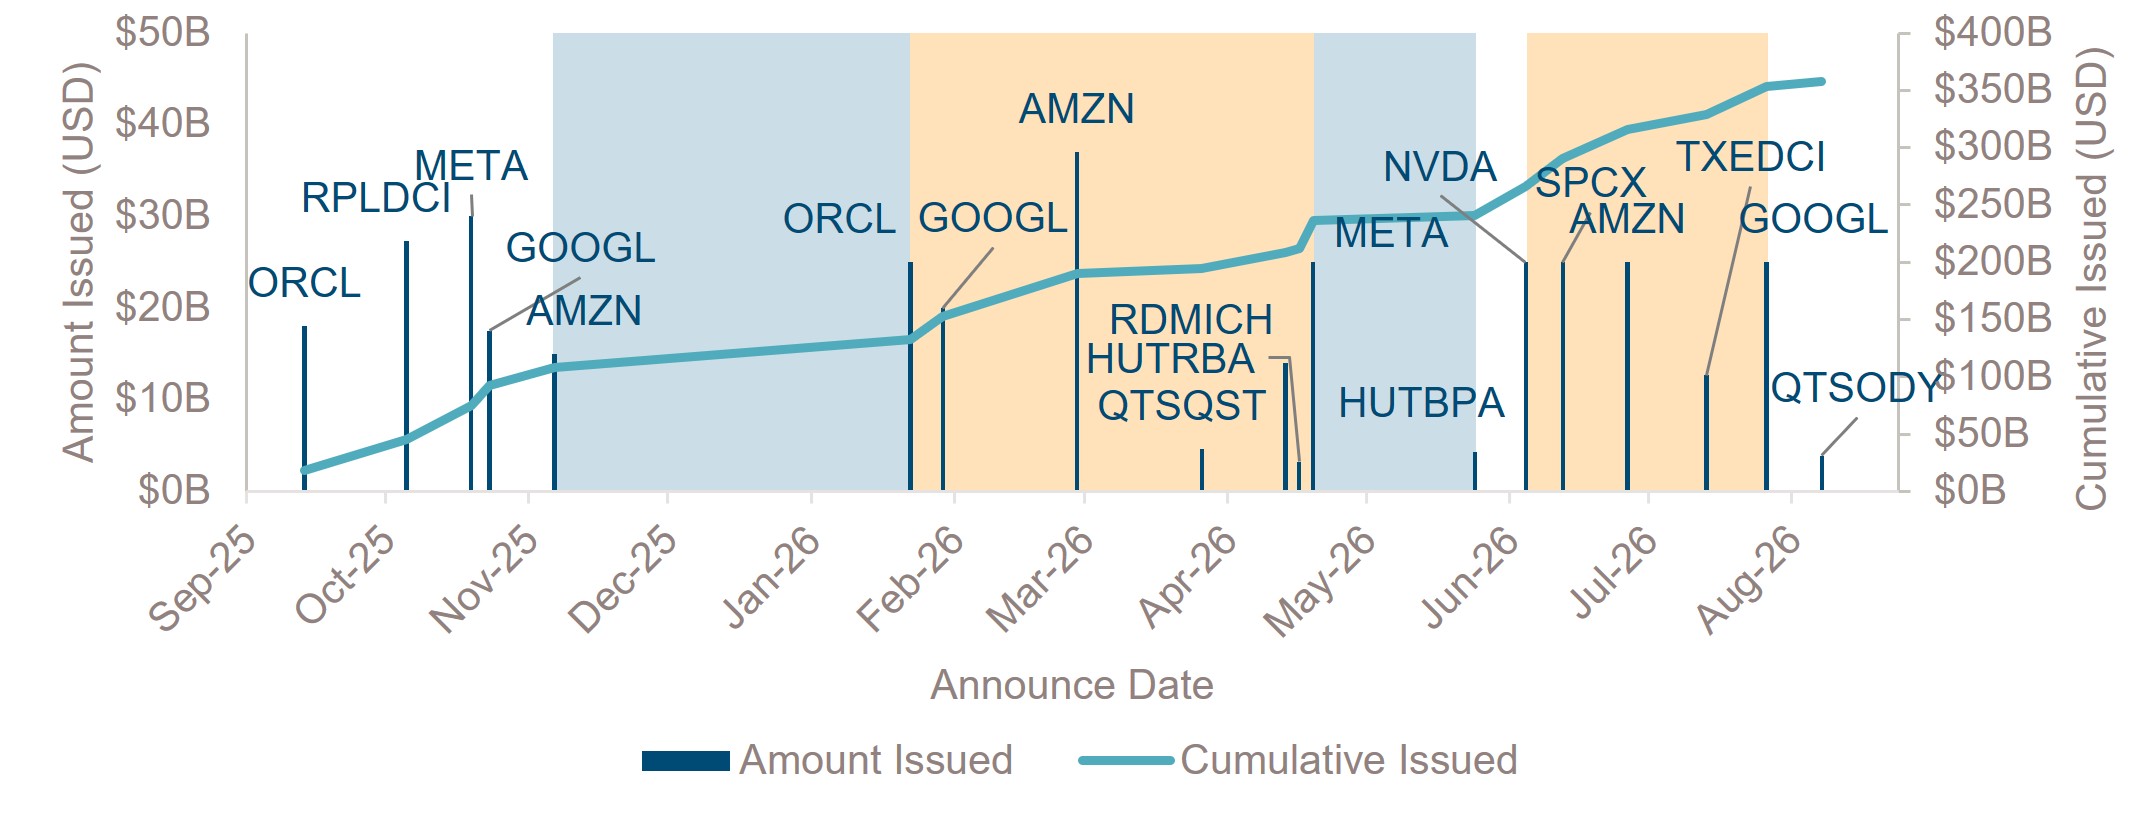
Figure 3: US technology credit vs. US investment grade
2. What does this mean for investors?
With hyperscaler debt issuance expected to more than double from 2025 levels in 2026, and forecasts pointing to a further c.60% increase in 20271, the supply-driven adjustment may not be over and further bouts of spread pressure are possible. But issuance is unlikely to arrive evenly.
For active managers, the opportunity is not simply that technology spreads are wider, but to dynamically adjust exposure as the market moves between periods of heavy supply and digestion – while distinguishing temporary technical pressure from deterioration in underlying credit fundamentals.
At the same time, the market may evolve. Clearer communication from hyperscalers around their financing needs and a more predictable issuance cadence could help investors prepare for future supply and allow the market to absorb it more efficiently. Encouragingly, we are already seeing early signs of this from some issuers.
References to specific companies is for illustrative purposes only and does not reflect the holdings of any specific past or current portfolio or account.
Sources: Fig. 2. Bloomberg, as of August 18, 2026. Fig 3. ICE Index Platform, as of September 16, 2026. US IG – ICE BofA US Investment Grade Corporate Index (C0A0), ICE BofA US Technology & Electronics Index (CITE). Indices used are the best proxy for subject under discussion. For illustrative purposes only. 1. Reuters, as of September 22, 2026. “Corporate bond buyers get picky with flood of AI debt”
This material is not intended to be relied upon as a forecast, research, or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or to adopt any investment strategy. The opinions expressed by Muzinich & Co. are as of September 2026 and may change without notice.
--------
Index descriptions
CITE - ICE BofA US Technology & Electronics Index is a subset of ICE BofA US Corporate Index including all securities of Technology & Electronics issuers.
C0A0 - The ICE BofA US Corporate Index tracks the performance of US dollar denominated investment grade corporate debt publicly issued in the US domestic market. Qualifying securities must have an investment grade rating (based on an average of Moody’s, S&P and Fitch), at least 18 months to final maturity at the time of issuance, at least one year remaining term to final maturity as of the rebalancing date, a fixed coupon schedule and a minimum amount outstanding of $250 million.
Important information
Muzinich and/or Muzinich & Co. referenced herein is defined as Muzinich & Co., Inc. and its affiliates. Muzinich views and opinions. This material has been produced for information purposes only and as such the views contained herein are not to be taken as investment advice. Opinions are as of date of publication and are subject to change without reference or notification to you. Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy. The value of investments and the income from them may fall as well as rise and is not guaranteed and investors may not get back the full amount invested. Rates of exchange may cause the value of investments to rise or fall.
Any research in this document has been obtained and may have been acted on by Muzinich for its own purpose. The results of such research are being made available for information purposes and no assurances are made as to their accuracy. Opinions and statements of financial market trends that are based on market conditions constitute our judgment and this judgment may prove to be wrong. The views and opinions expressed should not be construed as an offer to buy or sell or invitation to engage in any investment activity, they are for information purposes only.
This discussion material contains forward-looking statements, which give current expectations of future activities and future performance. Any or all forward-looking statements in this material may turn out to be incorrect. They can be affected by inaccurate assumptions or by known or unknown risks and uncertainties. Although the assumptions underlying the forward-looking statements contained herein are believed to be reasonable, any of the assumptions could be inaccurate and, therefore, there can be no assurances that the forward-looking statements included in this discussion material will prove to be accurate. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation that the objectives and plans discussed herein will be achieved. Further, no person undertakes any obligation to revise such forward-looking statements to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events.
United Arab Emirates (UAE): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the UAE. It is intended solely for Professional Investors and should not be relied upon by any other person. This material has not been reviewed or approved by the UAE Securities and Commodities Authority, the UAE Central Bank or any other relevant authority. Nothing contained herein constitutes investment, legal, tax or other professional advice. Recipients should make their own independent assessment where appropriate.
Abu Dhabi Global Market (ADGM): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the ADGM. It is intended solely for Professional Clients (as defined by the Financial Services Regulatory Authority) and should not be relied upon by any other person. This material has not been reviewed or approved by the Financial Services Regulatory Authority or any other relevant authority in the UAE.
United States: This material is for Institutional Investor use only – not for retail distribution. Muzinich & Co., Inc. is a registered investment adviser with the Securities and Exchange Commission (SEC). Muzinich & Co., Inc.’s being a Registered Investment Adviser with the SEC in no way shall imply a certain level of skill or training or any authorization or approval by the SEC.
Issued in the European Union by Muzinich & Co. (Ireland) Limited, which is authorized and regulated by the Central Bank of Ireland. Registered in Ireland, Company Registration No. 307511. Registered address: 32 Molesworth Street, Dublin 2, D02 Y512, Ireland. Issued in Switzerland by Muzinich & Co. (Switzerland) AG. Registered in Switzerland No. CHE-389.422.108. Registered address: Tödistrasse 5, 8002 Zurich, Switzerland. Issued in Singapore and Hong Kong by Muzinich & Co. (Singapore) Pte. Limited, which is licensed and regulated by the Monetary Authority of Singapore. Registered in Singapore No. 201624477K. Registered address: 6 Battery Road, #26-05, Singapore, 049909. Issued in all other jurisdictions (excluding the U.S.) by Muzinich & Co. Limited. which is authorized and regulated by the Financial Conduct Authority. Registered in England and Wales No. 3852444. Registered address: 8 Hanover Street, London W1S 1YQ, United Kingdom. 2026-09-30-19534
By clicking "Submit", I am (i) signing up to receive the Opinion Pieces from the "Opinions" page of the Muzinich & Co website, (ii) representing that the above information is true and accurate and (iii) agreeing to join the Muzinich & Co mailing list. I understand that Muzinich & Co will not add retail investors or individuals with personal email addresses to its mailing list and represent that I am not a retail investor. By providing my personal and professional information I am consenting to its use and disclosure in accordance with the Muzinich & Co. Privacy Policy. I understand that I may withdraw my consent and unsubscribe from receiving future communications by clicking "Unsubscribe" from the emails that are sent to me from Muzinich & Co.
Aug 06, 2026
After years of unusually flat credit spread curves, the market is beginning to differentiate more clearly between short- and longer-dated risk. As issuance, rate uncertainty and technical factors reshape valuations, the front end continues to offer a compelling balance of carry and resilience argue Ian Horn and Eric Schure.

Jul 07, 2026
Is it time to rethink the front end of the curve?
Short-duration investment grade has traditionally been viewed as a defensive allocation, helping investors manage interest rate risk and preserve capital. In our latest podcast, Portfolio Manager Ian Horn discusses why short-duration credit can offer more than defence.
Jun 30, 2026
Beyond cash: The case for short-duration crossover credit
As investors seek alternatives to low-yielding cash and rate-sensitive fixed income, short-duration global credit strategies are attracting attention. As investors seek alternatives to low-yielding cash and rate-sensitive fixed income, short-duration global credit strategies are attracting attention.