Muzinich Weekly Market Comment: Tempting Fate
Insight
November 16, 2026
If you have any feedback on this article or are interested in subscribing to our content, please contact us at opinions@muzinich.com or fill out the form on the right hand side of this page.
--------
It was a good week for risk assets, but a much tougher one for safe havens. Government bond yields rose across the world, with US Treasuries adjusting most violently. In credit, spreads tightened and high yield outperformed its investment grade peer, while the investor go-to safe havens came under pressure, with gold hitting a one-year low and the Swiss franc ending as the worst-performing G10 currency vs. the US dollar. Sentiment did improve, with our preferred gauge, the VIX, falling steadily through the week after closing the prior week at “fright mode” levels.
That said, this wasn’t a typical risk-on “melt-up” rally, more a relief trade. Further military operations in Iran now look unlikely, and there is even some hope that Ukraine and Russia are moving in the right direction toward a settlement. Earnings and economic data, meanwhile, confirmed that robust positive momentum remains in place.
In China, investors are increasingly using the trade data report as a lead indicator for the health of the AI cycle, given the sector’s reliance on Chinese hardware manufacturing. October showed no sign of an AI slowdown. Exports rose 35.2% year-over-year (YoY), a second consecutive month of gains above 35%, with high-tech shipments jumping 66.6%, accounting for just over half of headline export growth. Imports also accelerated to 41.6% YoY, and here too tech-related products played a key role.[1]
Economists, meanwhile, watched the monthly price reports for signs that China will start exporting inflation, and October carried a warning. Producer inflation accelerated to its fastest pace since June 2022, with prices at the factory gate climbing 5.7%, lifting costs for manufacturers. The details are more reassuring, as only half of the 30 key sectors tracked recorded price gains. Nor has inflation fed through to consumer goods, with the Consumer Price Index (CPI) slipping more than forecast to 0.7% YoY. Taken together, this looks like a commodity-driven supply shock rather than broad-based demand-pull inflation.[2]
In the UK, it was good news for growth-oriented assets, less so for the Gilt market. The provisional third quarter numbers continued to show no sign of a slowdown despite the supply-side energy shock, with the economy expanding 0.7% in 3Q26, faster than the 0.5% in 2Q26. Services did the heavy lifting, up 0.9% and led by business-facing sectors, while production added just 0.1% and construction fell 0.7%. Notably, the Office for National Statistics (ONS) reported that many of the firms with the biggest jumps in sales are doing AI and cloud work, an echo of the China trade data above. On the expenditure side, household and government consumption each rose a solid 0.6%, while gross fixed capital formation increased 1.7%, driven by machinery, equipment and transport. [3]
For the US, the challenge is finding an economic report that isn’t running hot. As our Chart of the Week shows, the Citi US Economic Surprise Index sits at 71; economic data have rarely beaten consensus this consistently or this widely outside the Covid rebound. Last week it was the turn of the consumer price data, the last CPI report before the Federal Open Market Committee (FOMC) meets on 8 - 9 December. Tempting fate, Federal Reserve (Fed) Governor Christopher Waller, a permanent voter and as recently as January, the Committee’s most prominent dove, when he dissented in favor of a cut, said in London hours before the release that a half-point hike should be on the table in December if core CPI came in “around 0.3”.[4]
There was no YoY figure in this report because last year’s October print never happened, thanks to the government shutdown. Headline CPI rose 0.35% in October and core came in at 0.30%, both above consensus forecasts. The three-month annualized core rate picked up to 3.7% (vs. 3.4%), while the six-month rate dipped to 2.7% (vs. 2.9%).[5] This report, alongside the previous week’s strong payrolls, may have all but sealed a December hike. Overnight Index Swap (OIS) pricing has moved from a 73% chance at the start of the month to 108% on Friday, 13 November 2026, with the overshoot reflecting a small probability of a 50 basis point (bp) move. Investors have also added a hike to their 2027 path, now looking for two 25bp increases to take the fed funds rate to 4.75% rather than one to 4.50%, front-loaded through the first quarter.[6]
Chart of the Week: US Economy Running Hot
Citi US Economic Surprise Index, weekly
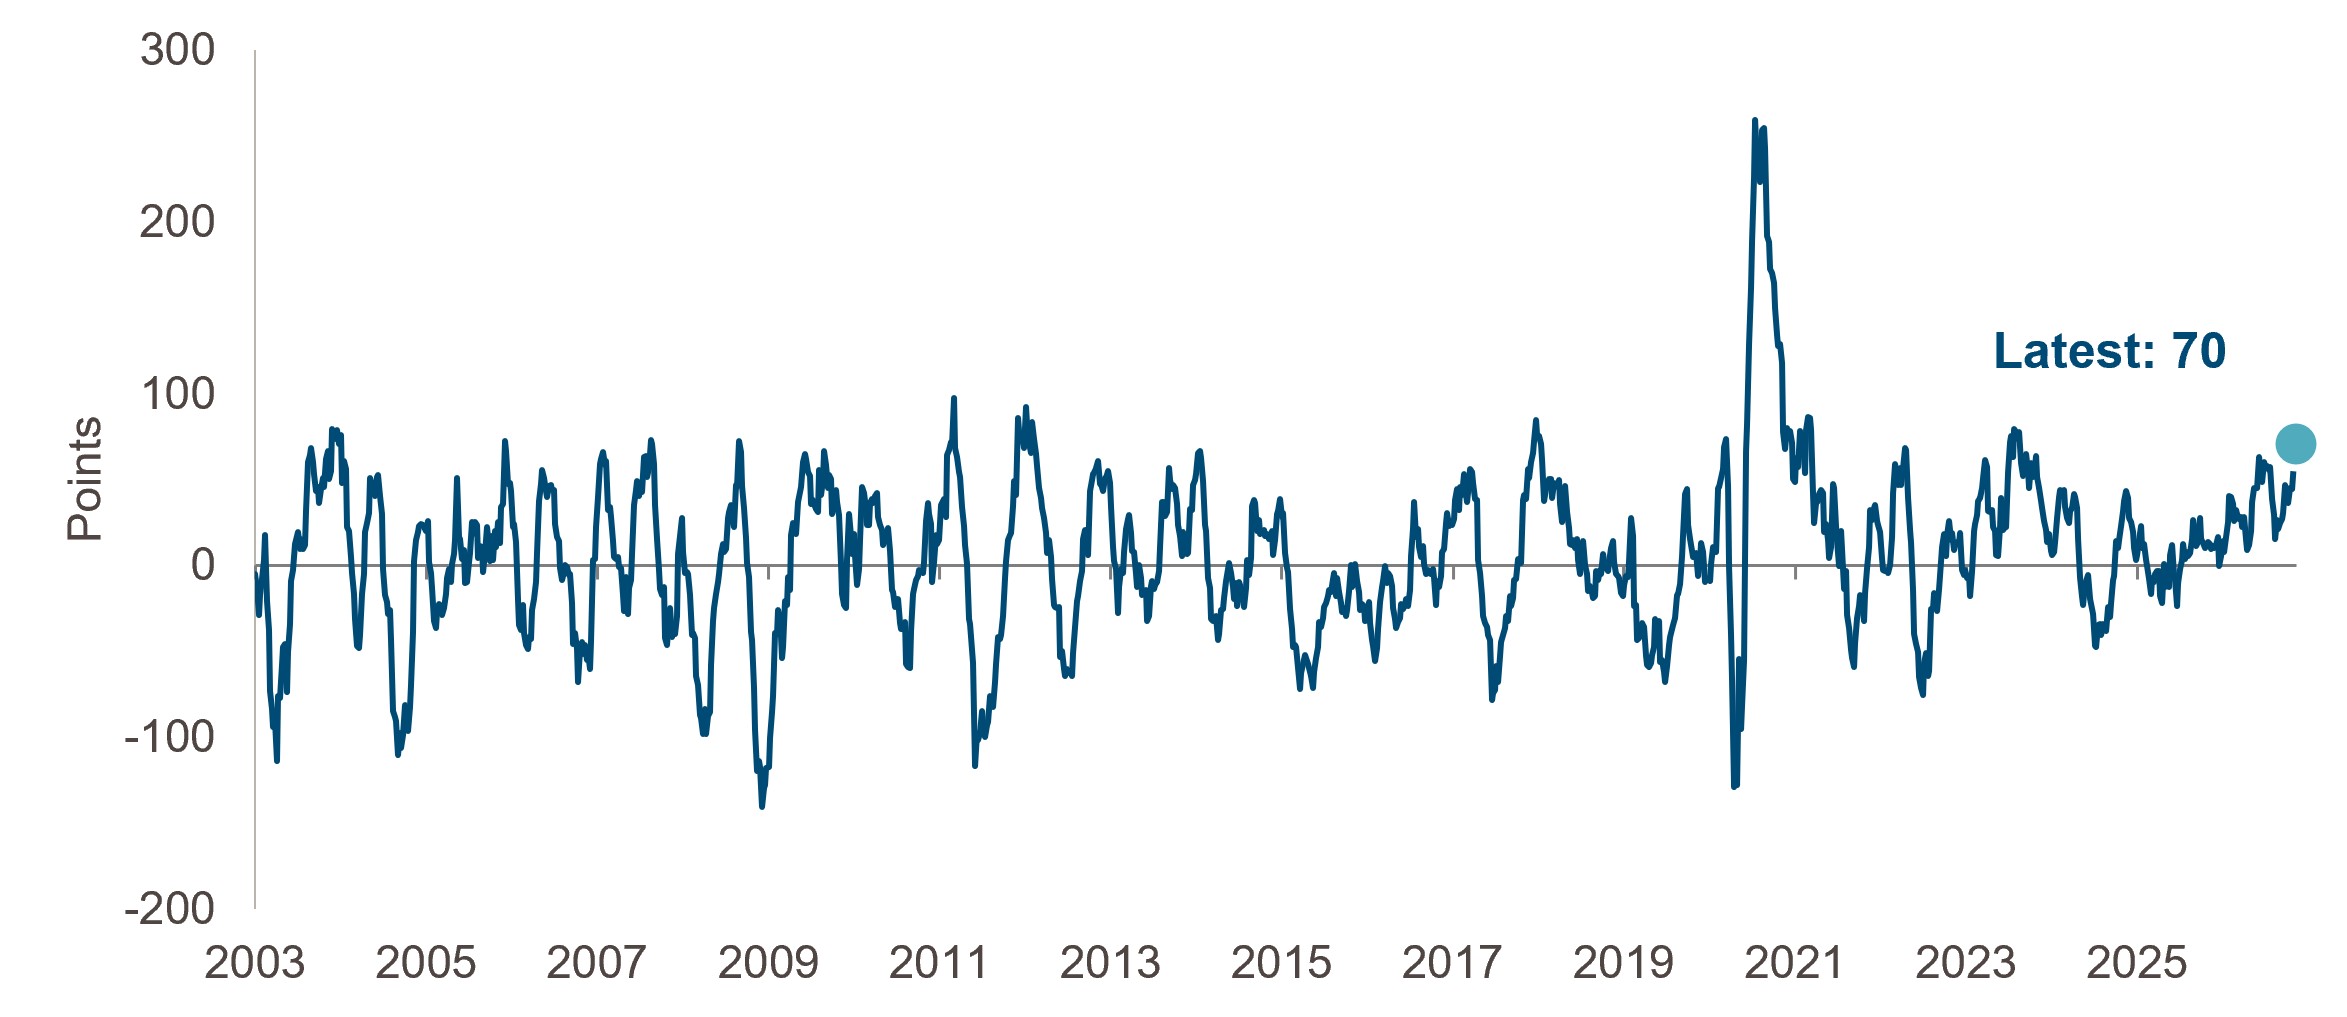 Source: Citi, Bloomberg, as of November 13, 2026. Muzinich views and opinions are subject to change. For illustrative purposes only, not to be construed as investment advice or an invitation to engage in any investment activity.
Past performance is not a reliable indicator of current or future results.
References
[1] Bloomberg, “CHINA REACT: AI-Related Trade Drives Exports, Shows Risks,” November 9. 2026
[2] Bloomberg, “China’s ‘Bad Inflation’ Gets Entrenched but Deflation Risks Lurk,” November 9. 2026
[3] Office for National Statistics, “GDP first quarterly estimate, UK: July to September 2026,” November 12, 2026
[4] Bloomberg, “US Core CPI Rises by More Than Forecast, Supporting Fed Hike,” November 10, 2026
[5] Bloomberg, “US REACT: Hot CPI Probably Sealed the Deal for December Hike,” November 10. 2026
[6] Bloomberg, as of November 13, 2026
--------
Important information
Muzinich & Co., “Muzinich” and/or the “Firm” referenced herein is defined as Muzinich & Co. Inc. and its affiliates. This material has been produced for information purposes only and as such the views contained herein are not to be taken as investment advice. Opinions are as of date of publication and are subject to change without reference or notification to you. Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy. The value of investments and the income from them may fall as well as rise and is not guaranteed and investors may not get back the full amount invested. Rates of exchange may cause the value of investments to rise or fall. Emerging Markets may be more risky than more developed markets for a variety of reasons, including but not limited to, increased political, social and economic instability, heightened pricing volatility and reduced market liquidity. Any research in this document has been obtained and may have been acted on by Muzinich for its own purpose. The results of such research are being made available for information purposes and no assurances are made as to their accuracy. Opinions and statements of financial market trends that are based on market conditions constitute our judgment and this judgment may prove to be wrong. The views and opinions expressed should not be construed as an offer to buy or sell or invitation to engage in any investment activity, they are for information purposes only. Any forward-looking information or statements expressed in the above may prove to be incorrect. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation that the objectives and plans discussed herein will be achieved. Muzinich gives no undertaking that it shall update any of the information, data and opinions contained in the above.
United States: This material is for Institutional Investor use only – not for retail distribution. Muzinich & Co., Inc. is a registered investment adviser with the Securities and Exchange Commission (SEC). Muzinich & Co., Inc.’s being a Registered Investment Adviser with the SEC in no way shall imply a certain level of skill or training or any authorization or approval by the SEC.
United Arab Emirates (UAE): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the UAE. It is intended solely for Professional Investors and should not be relied upon by any other person. This material has not been reviewed or approved by the UAE Securities and Commodities Authority, the UAE Central Bank or any other relevant authority. Nothing contained herein constitutes investment, legal, tax or other professional advice. Recipients should make their own independent assessment where appropriate.
Abu Dhabi Global Market (ADGM): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the ADGM. It is intended solely for Professional Clients (as defined by the Financial Services Regulatory Authority) and should not be relied upon by any other person. This material has not been reviewed or approved by the Financial Services Regulatory Authority or any other relevant authority in the UAE.
Issued in the European Union by Muzinich & Co. (Ireland) Limited, which is authorized and regulated by the Central Bank of Ireland. Registered in Ireland, Company Registration No. 307511. Registered address: 32 Molesworth Street, Dublin 2, D02 Y512, Ireland. Issued in Switzerland by Muzinich & Co. (Switzerland) AG. Registered in Switzerland No. CHE-389.422.108. Registered address: Tödistrasse 5, 8002 Zurich, Switzerland. Issued in Singapore and Hong Kong by Muzinich & Co. (Singapore) Pte. Limited, which is licensed and regulated by the Monetary Authority of Singapore. Registered in Singapore No. 201624477K. Registered address: 6 Battery Road, #26-05, Singapore, 049909. Issued in all other jurisdictions (excluding the U.S.) by Muzinich & Co. Limited. which is authorized and regulated by the Financial Conduct Authority. Registered in England and Wales No. 3852444. Registered address: 8 Hanover Street, London W1S 1YQ, United Kingdom.
By clicking "Submit", I am (i) signing up to receive the Opinion Pieces from the "Opinions" page of the Muzinich & Co website, (ii) representing that the above information is true and accurate and (iii) agreeing to join the Muzinich & Co mailing list. I understand that Muzinich & Co will not add retail investors or individuals with personal email addresses to its mailing list and represent that I am not a retail investor. By providing my personal and professional information I am consenting to its use and disclosure in accordance with the Muzinich & Co. Privacy Policy. I understand that I may withdraw my consent and unsubscribe from receiving future communications by clicking "Unsubscribe" from the emails that are sent to me from Muzinich & Co.
Nov 13, 2026
Muzinich Asset Allocation Group Monthly Update - November 2026
Please click to watch our latest Asset Allocation Group video update for the month of November 2026.
Nov 09, 2026
Muzinich Weekly Market Comment: The Executive Years – Two Years, One Pen
It was a good week for healthcare and green energy, and for the Democrats. Less so for AI, fossil fuels and defence, and for the Republicans.
Nov 09, 2026
Corporate Credit Snapshot - November 2026
October was a volatile month, with global credit delivering mostly positive returns. Equities sold off as mixed results from the largest technology companies—and disappointment over their cash flow amid heavy AI spending—weighed on sentiment.