AAA CLOs: High-quality floating rate income for a volatile rate environment
Insight
September 29, 2026
If you have any feedback on this article or are interested in subscribing to our content, please contact us at opinions@muzinich.com or fill out the form on the right hand side of this page.
--------
After several years in which investors have had to contend with rapidly changing interest-rate expectations, the outlook for monetary policy remains uncertain. Inflation has moderated from its post-pandemic highs, but it has proved sticky in places, while resilient economic growth, fiscal expansion and shifting central-bank expectations continue to generate volatility across fixed rate bond markets.
For fixed-income investors, this creates a familiar dilemma: how to capture attractive income without taking excessive credit or interest-rate risk.
We believe AAA-rated collateralised loan obligations (CLOs) can offer a compelling solution. Combining high credit quality with floating-rate coupons and attractive income potential, the asset class can provide a useful complement to traditional fixed-rate bond allocations. And through an actively managed UCITS ETF, investors can access this exposure in a liquid and transparent format.
Why floating rate – and why now?
For the decade following the Global Financial Crisis, investors were rewarded for taking duration risk as interest rates declined and remained low. Today, the picture is more complicated.
Markets continue to reassess the likely path of monetary policy as central banks balance inflation against economic growth. At the same time, increased government borrowing and fiscal spending are putting greater focus on the longer end of sovereign yield curves. The result has been continued volatility in bond yields while the direction of short-term policy rates has trended higher.
This matters because conventional fixed-rate bonds are sensitive to movements in government bond yields. When yields rise, bond prices fall, with longer-duration securities generally experiencing the greatest price impact.
AAA rated collateralised loan obligations (CLO) are different. Their coupons are floating rate, typically comprising a reference rate plus a fixed credit spread. As a result, their income adjusts quarterly as prevailing short-term interest rates change and they have very low interest-rate duration risk.
For investors, this can provide two important benefits.
First, floating-rate exposure can help reduce sensitivity to movements in rates. Investors do not need to make a large directional call on interest rates to generate income. In an environment where the timing and extent of future rate changes remain uncertain, we believe that is particularly valuable.
Second, floating-rate assets can provide a relatively stable source of income. While coupons will move as short-term rates change, investors continue to receive the contractual spread over the reference rate. This can make the income component of returns an important potential source of resilience.
In our view, that combination of attractive income and low duration makes floating-rate credit particularly relevant today and is a major factor in the stability of the asset class in the current rate environment.
High-quality exposure to corporate credit
A CLO is a securitised portfolio primarily comprising broadly syndicated senior secured corporate loans. The cashflows generated by those loans are distributed across different layers, or tranches, according to a predefined priority of payments.
AAA-rated tranches sit at the top of that capital structure. They receive payments before more junior tranches and benefit from substantial structural protections, as well as their seniority in the capital structure.
This creates a significant buffer against deterioration in the CLO’s underlying loan portfolio. CLOs are diversified across many corporate borrowers, industries and individual loans, reducing exposure to any single company.
These protections are reflected in the highest credit rating assigned to AAA tranches. However, AAA does not mean risk-free. CLOs remain exposed to risks including credit deterioration in the underlying loan portfolio, changes in market liquidity and spreads, structural complexity and mark-to-market volatility.
Understanding those risks - and the differences between individual CLOs - is therefore important.
One of the most interesting characteristics of AAA CLOs is the income they can offer relative to other highly rated fixed-income assets.
The additional spread partly reflects the perceived complexity of the CLO structure and the specialist expertise required to analyse the asset class, rather than simply compensation for expected credit losses.
This can create an attractive opportunity for investors able to conduct detailed analysis of individual CLO structures, collateral pools and managers.
In effect, investors can potentially capture an additional source of spread while remaining at the top of the CLO capital structure. For investors seeking high-quality income, we believe this can make AAA CLOs an attractive diversifier when compared to government bonds and money markets, as well as a complement to traditional investment-grade corporate credit.
Figure 1 – AAA CLO yields vs. similarly rated traditional fixed-income assets
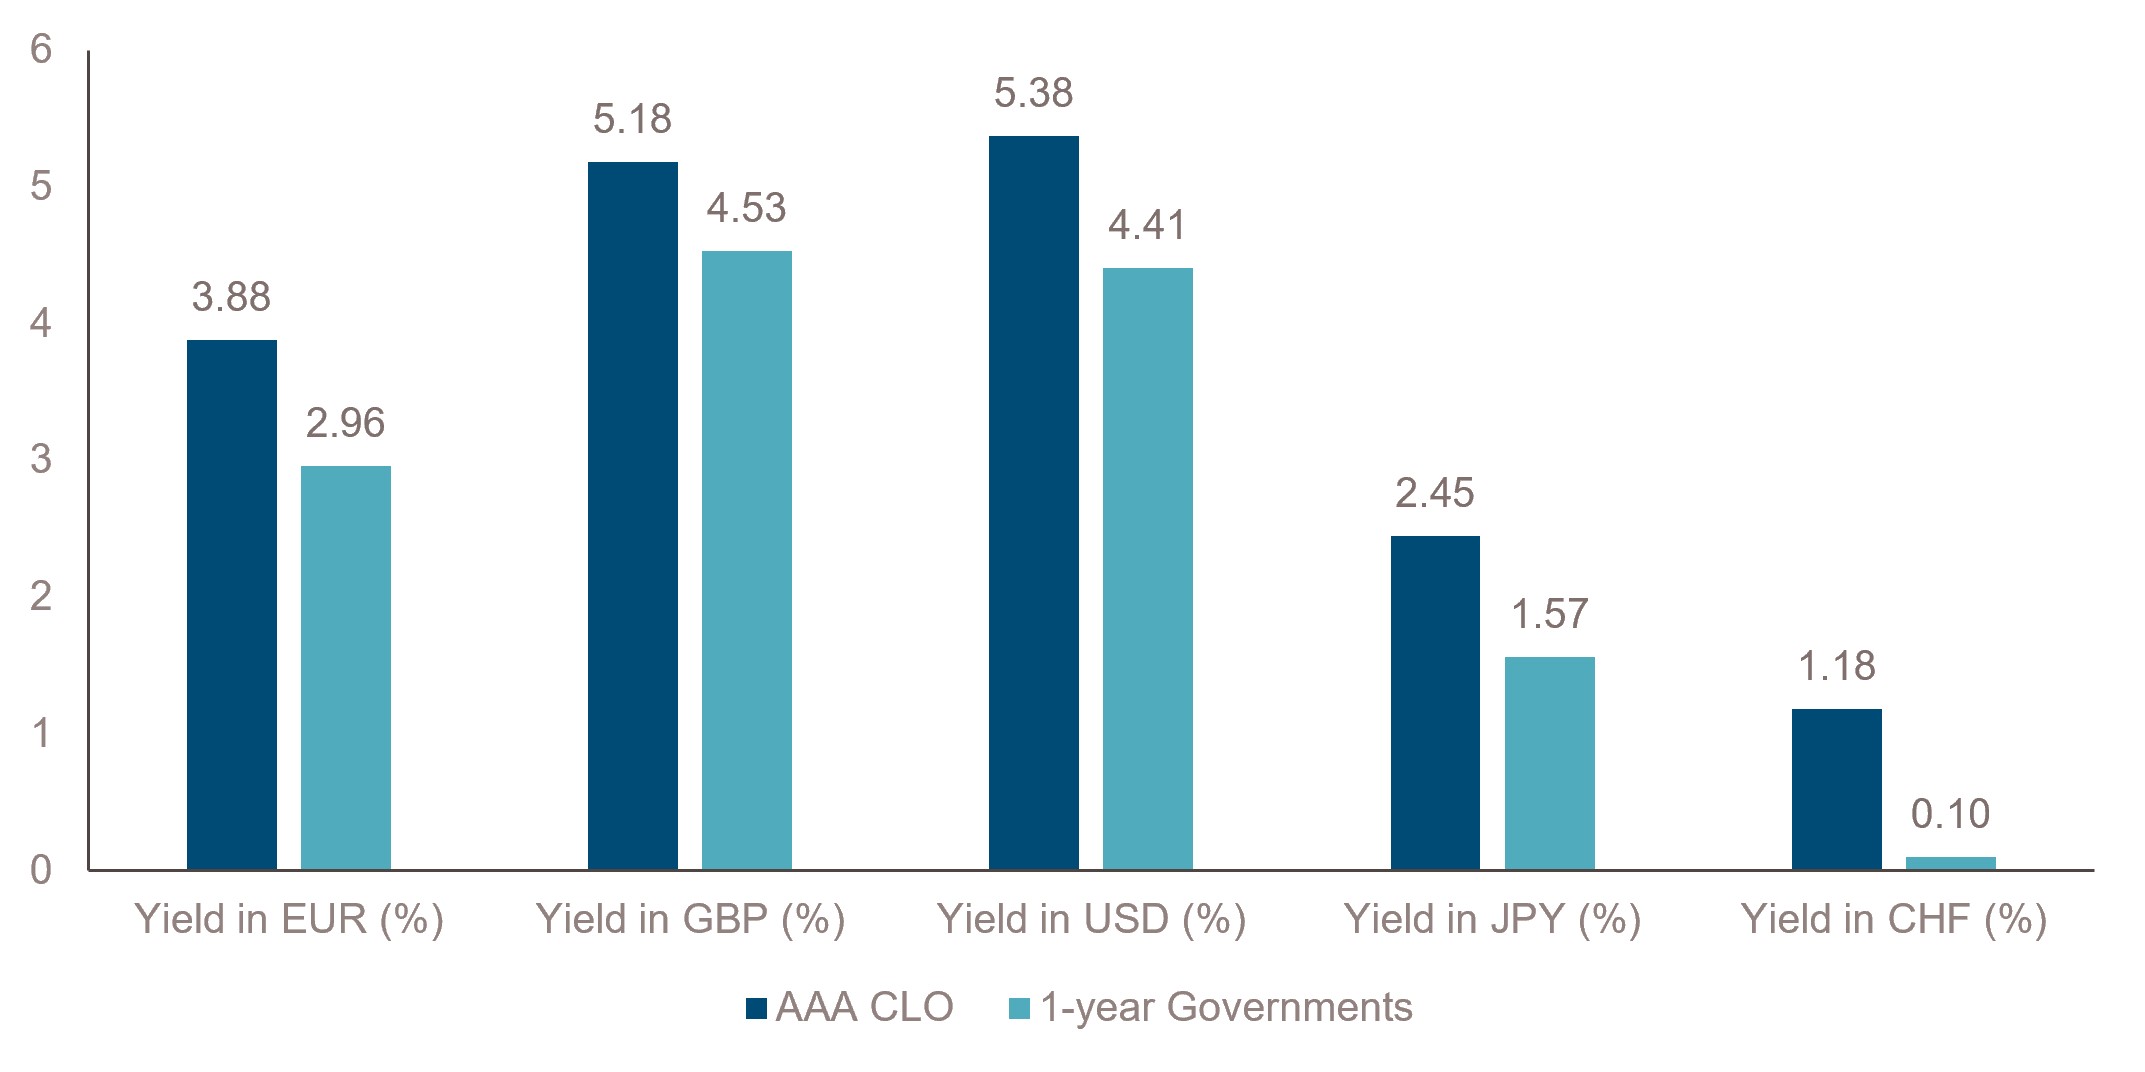
Source: Muzinich analysis using data from J.P. Morgan CLOIE, ICE Index Platform and Bank of America, as of 21st September 2026. AAA CLO EUR yield is based on the J.P. Morgan EUR CLOIE AAA Index, unhedged EUR yield-to-worst. GBP, USD, JPY and CHF AAA CLO yields are illustrative currency-hedged yield equivalents calculated by Muzinich by adjusting the EUR AAA CLO yield using Bloomberg FX hedge data: FXHCEUGB, FXHCEUUS, FXHCEUJP and FXHCEUCF. Government bond proxies are Bloomberg 1-year government yield indices: EUR = YCGT0016, GBP = YCGT0022, USD = YCGT0025, JPY = YCGT0018 and CHF = YCGT0082. For illustrative purposes only.
In each of the five currencies shown, AAA CLO yields sat above 1-year government bond yields.
Although securities within the asset class may share the same AAA rating, they are not identical.
CLOs differ by manager, portfolio construction, documentation, structural protections, underlying collateral and position within their lifecycle. These differences can affect risk, liquidity and relative value.
Active management therefore plays an important role. Detailed fundamental analysis can help identify stronger structures and managers while avoiding securities where the available spread does not adequately compensate for the risks.
It can also allow a portfolio to respond as market conditions change. Periods of volatility can create pricing dislocations between CLOs with similar ratings but different underlying characteristics, potentially providing opportunities for active managers to improve portfolio income or quality.
Making CLOs easier to access
Historically, accessing the CLO market directly has presented practical challenges for many investors. Individual securities can trade in large denominations; the structures require specialist analysis and building a diversified portfolio can require significant resources.
A UCITS ETF can remove some of those barriers.
By combining a diversified portfolio of AAA CLOs with the accessibility of an exchange-traded vehicle, an ETF can offer investors daily and intra-day liquidity, transparency of holdings and pricing as well as straightforward portfolio implementation and relative stability of NAV in a volatile rates environment.
It also allows investors to incorporate AAA CLO exposure alongside more familiar fixed-income holdings without having to build and manage a portfolio of individual CLO securities themselves.
A different source of fixed-income resilience
The case for fixed income remains strong, but we believe the composition of fixed-income portfolios deserves careful consideration.
Uncertainty around inflation, fiscal policy and the path of interest rates means investors may continue to experience periods of significant fixed rate bond volatility. Taking more duration is not necessarily the only way to generate attractive returns.
AAA CLOs offer a different proposition: high credit quality, attractive income potential and floating-rate exposure with very limited interest-rate duration.
For investors seeking to maintain income while reducing their sensitivity to swings in rates, we believe an actively managed AAA CLO ETF can offer a compelling addition to a diversified fixed-income portfolio.
------
Important information
Muzinich and/or Muzinich & Co. referenced herein is defined as Muzinich & Co., Inc. and its affiliates. Muzinich views and opinions. This material has been produced for information purposes only and as such the views contained herein are not to be taken as investment advice. Opinions are as of date of publication and are subject to change without reference or notification to you. Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy. The value of investments and the income from them may fall as well as rise and is not guaranteed and investors may not get back the full amount invested. Rates of exchange may cause the value of investments to rise or fall.
Any research in this document has been obtained and may have been acted on by Muzinich for its own purpose. The results of such research are being made available for information purposes and no assurances are made as to their accuracy. Opinions and statements of financial market trends that are based on market conditions constitute our judgment and this judgment may prove to be wrong. The views and opinions expressed should not be construed as an offer to buy or sell or invitation to engage in any investment activity, they are for information purposes only.
This discussion material contains forward-looking statements, which give current expectations of future activities and future performance. Any or all forward-looking statements in this material may turn out to be incorrect. They can be affected by inaccurate assumptions or by known or unknown risks and uncertainties. Although the assumptions underlying the forward-looking statements contained herein are believed to be reasonable, any of the assumptions could be inaccurate and, therefore, there can be no assurances that the forward-looking statements included in this discussion material will prove to be accurate. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation that the objectives and plans discussed herein will be achieved. Further, no person undertakes any obligation to revise such forward-looking statements to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events.
United Arab Emirates (UAE): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the UAE. It is intended solely for Professional Investors and should not be relied upon by any other person. This material has not been reviewed or approved by the UAE Securities and Commodities Authority, the UAE Central Bank or any other relevant authority. Nothing contained herein constitutes investment, legal, tax or other professional advice. Recipients should make their own independent assessment where appropriate.
Abu Dhabi Global Market (ADGM): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the ADGM. It is intended solely for Professional Clients (as defined by the Financial Services Regulatory Authority) and should not be relied upon by any other person. This material has not been reviewed or approved by the Financial Services Regulatory Authority or any other relevant authority in the UAE.
United States: This material is for Institutional Investor use only – not for retail distribution. Muzinich & Co., Inc. is a registered investment adviser with the Securities and Exchange Commission (SEC). Muzinich & Co., Inc.’s being a Registered Investment Adviser with the SEC in no way shall imply a certain level of skill or training or any authorization or approval by the SEC.
Issued in the European Union by Muzinich & Co. (Ireland) Limited, which is authorized and regulated by the Central Bank of Ireland. Registered in Ireland, Company Registration No. 307511. Registered address: 32 Molesworth Street, Dublin 2, D02 Y512, Ireland. Issued in Switzerland by Muzinich & Co. (Switzerland) AG. Registered in Switzerland No. CHE-389.422.108. Registered address: Tödistrasse 5, 8002 Zurich, Switzerland. Issued in Singapore and Hong Kong by Muzinich & Co. (Singapore) Pte. Limited, which is licensed and regulated by the Monetary Authority of Singapore. Registered in Singapore No. 201624477K. Registered address: 6 Battery Road, #26-05, Singapore, 049909. Issued in all other jurisdictions (excluding the U.S.) by Muzinich & Co. Limited. which is authorized and regulated by the Financial Conduct Authority. Registered in England and Wales No. 3852444. Registered address: 8 Hanover Street, London W1S 1YQ, United Kingdom. 2026-07-28-19099
By clicking "Submit", I am (i) signing up to receive the Opinion Pieces from the "Opinions" page of the Muzinich & Co website, (ii) representing that the above information is true and accurate and (iii) agreeing to join the Muzinich & Co mailing list. I understand that Muzinich & Co will not add retail investors or individuals with personal email addresses to its mailing list and represent that I am not a retail investor. By providing my personal and professional information I am consenting to its use and disclosure in accordance with the Muzinich & Co. Privacy Policy. I understand that I may withdraw my consent and unsubscribe from receiving future communications by clicking "Unsubscribe" from the emails that are sent to me from Muzinich & Co.