Muzinich Weekly Market Comment: Occam’s Razor
Insight
October 19, 2026
If you have any feedback on this article or are interested in subscribing to our content, please contact us at opinions@muzinich.com or fill out the form on the right hand side of this page.
--------
China came back from Golden Week with good news on two fronts. On trade, after two days of negotiations in Beijing, EU Trade Commissioner Maroš Šefčovič said the two sides had reached an understanding on three things: halving Chinese exports of hybrid and plug-in hybrid vehicles to the EU, improving EU access to the Chinese market, and further simplifying rare-earth export licensing[1]. They also agreed to keep discussing possible tariff cuts on certain goods under World Trade Organization rules, with a third round of talks scheduled for March 2027.
Meanwhile, on the prices front, China looks set to end three straight years of economy-wide deflation. Producer price inflation accelerated in September to 5.0% year-over-year (YoY) from 3.8% in August. That was the highest reading since June 2022. The pickup largely reflected renewed energy shocks from the Middle East and strong demand for AI hardware. The biggest increases were in petroleum processing, coal, non-ferrous metals, and IT equipment[2]. Firmer producer prices now look set to lift the annual GDP deflator into positive territory in 2026 for the first time since 2022, although this will not be confirmed until full-year GDP data are released in January 2027.
In Europe, the UK continues to defy expectations. GDP unexpectedly grew 0.1% in August, beating economists’ forecasts of a 0.1% contraction and marking the fourth straight month that growth has topped consensus. On a three-month basis, output rose 0.7%. The Office for National Statistics said a 1.2% surge in manufacturing output drove the August gain. Services were flat, though still better than expected, and construction declined[3]. This was the final GDP release before Chancellor John Healey delivers his first Budget on 28 October, against a tight fiscal position and a turbulent global market backdrop. International Monetary Fund chief economist Silvana Tenreyro said the UK stands out in the G7 for budget plans that stabilize debt and put the public finances on track to start shrinking the national debt. Her message to the UK was simply to “stay the course”[4].
The stronger-than-expected growth has likely not gone unnoticed at the Bank of England, strengthening the case for raising rates next month to contain inflation risks from the energy shock. Overnight index swap (OIS) markets are pricing a 92% chance that the Monetary Policy Committee hikes by 25 basis points (bps) to 4% on 5 November[5].
In the US, this week’s data sent a clear signal of continued price pressures—hardly music to the ears of an administration deep in campaign mode ahead of the midterms. Headline Consumer Price Index (CPI) accelerated to 0.65% in September, lifting the annual rate to 3.7%. Energy added 39 bps to the headline, as gasoline prices jumped 9.1%, the most since the outbreak of the Iran war. More worrying for the Federal Open Market Committee is likely the pickup in core CPI, which rose a stronger-than-expected 0.33%, taking the annual rate to 2.6%. Shelter accounted for about half of the increase (18 bps). Momentum is building. Annualized core inflation is now 3.4% over three months and 2.9% over six months, up from 2.0% and 2.6%, respectively[6]. Meanwhile, the Producer Price Index rose 1.3% month-over-month and 6.3% YoY[7].
Price pressures also showed up in retail sales. As the data are not adjusted for inflation, higher prices can flatter the headline, which rose 0.8% in September, with August revised up to 1.3%. However, excluding motor vehicles and gasoline, where price pressures have been strongest, sales rose a tepid 0.2%[8]. That suggests consumers are still willing to spend but may also be starting to cut back in the face of higher energy prices.
This week’s data pointed to rising prices and surprisingly resilient growth, so it may seem odd that government bond yields fell. Major curves bull-flattened, with 10-year yields down 14 bps in US Treasuries, 10 bps in French OATs, 9 bps in JGBs, and 6 bps in both Gilts and Bunds. Bull flattening often occurs during a growth scare or a flight to safety. This week, we believe investors circled back to one of our three fear themes for the final quarter: the cost of funding. This time it was the corporates’ turn under the microscope, with investors starting to spot cracks in the neocloud sector.
Neoclouds are newer cloud companies built just for AI. Amazon, Microsoft, and Google sell hundreds of cloud services, whereas neoclouds focus on renting out graphics processing units (GPUs), the chips used to train and run AI models. The largest is CoreWeave, which rents its computing power to large corporates on four- to six-year take-or-pay contracts.
Landlords build the data centers and connect the power. CoreWeave then leases the finished buildings, pays the rent and electricity, and fits them out with its own servers. It buys GPUs in huge volumes, mostly with borrowed money, and the chips serve as collateral for loans that are usually tied to a long-term customer contract. That business model leaves neoclouds exposed to three main risks: a cooling in AI demand, GPUs losing value faster than expected, and higher interest rates.
With CoreWeave’s cost of funding in the US dollar public bond market touching 15% this week, investors began to question whether the company can keep expanding at its breathtaking pace. Over the next 12 months, the company is projected to generate around $10bn of operating cash flow, against roughly $45bn of required capex[9]. By extension, if that pace can no longer be funded, investors may begin to question whether the AI investment cycle, one of the main drivers of growth, is economically sustainable—hence the growth scare.
William of Ockham, a 14th-century friar from the Surrey village of Ockham, argued that we should not add assumptions beyond necessity. In other words, the simplest explanation is usually the best, a principle now known as Occam’s razor. Applied to bond markets, it suggests two variables will dominate the direction of government yields from here. Since March, energy prices have been the main variable to watch. Rising prices have been interpreted as inflationary, pushing yields higher. This week, however, energy prices moved sideways and put little pressure on yields. Instead, the notable outlier was the underperformance of technology stocks. In the US, the Nasdaq sold off over 3% this week, while the Dow Jones rose 1%. Technology-light European indices had a strong week, while the weakest performers were Asian technology markets, such as South Korea and Taiwan. The second variable, therefore, is the direction of technology stocks. A falling technology market can be interpreted as a signal of weaker growth, putting downward pressure on government bond yields. See the Chart of the Week.
Chart of the Week: Do Technology Fears Trigger Growth Scares?
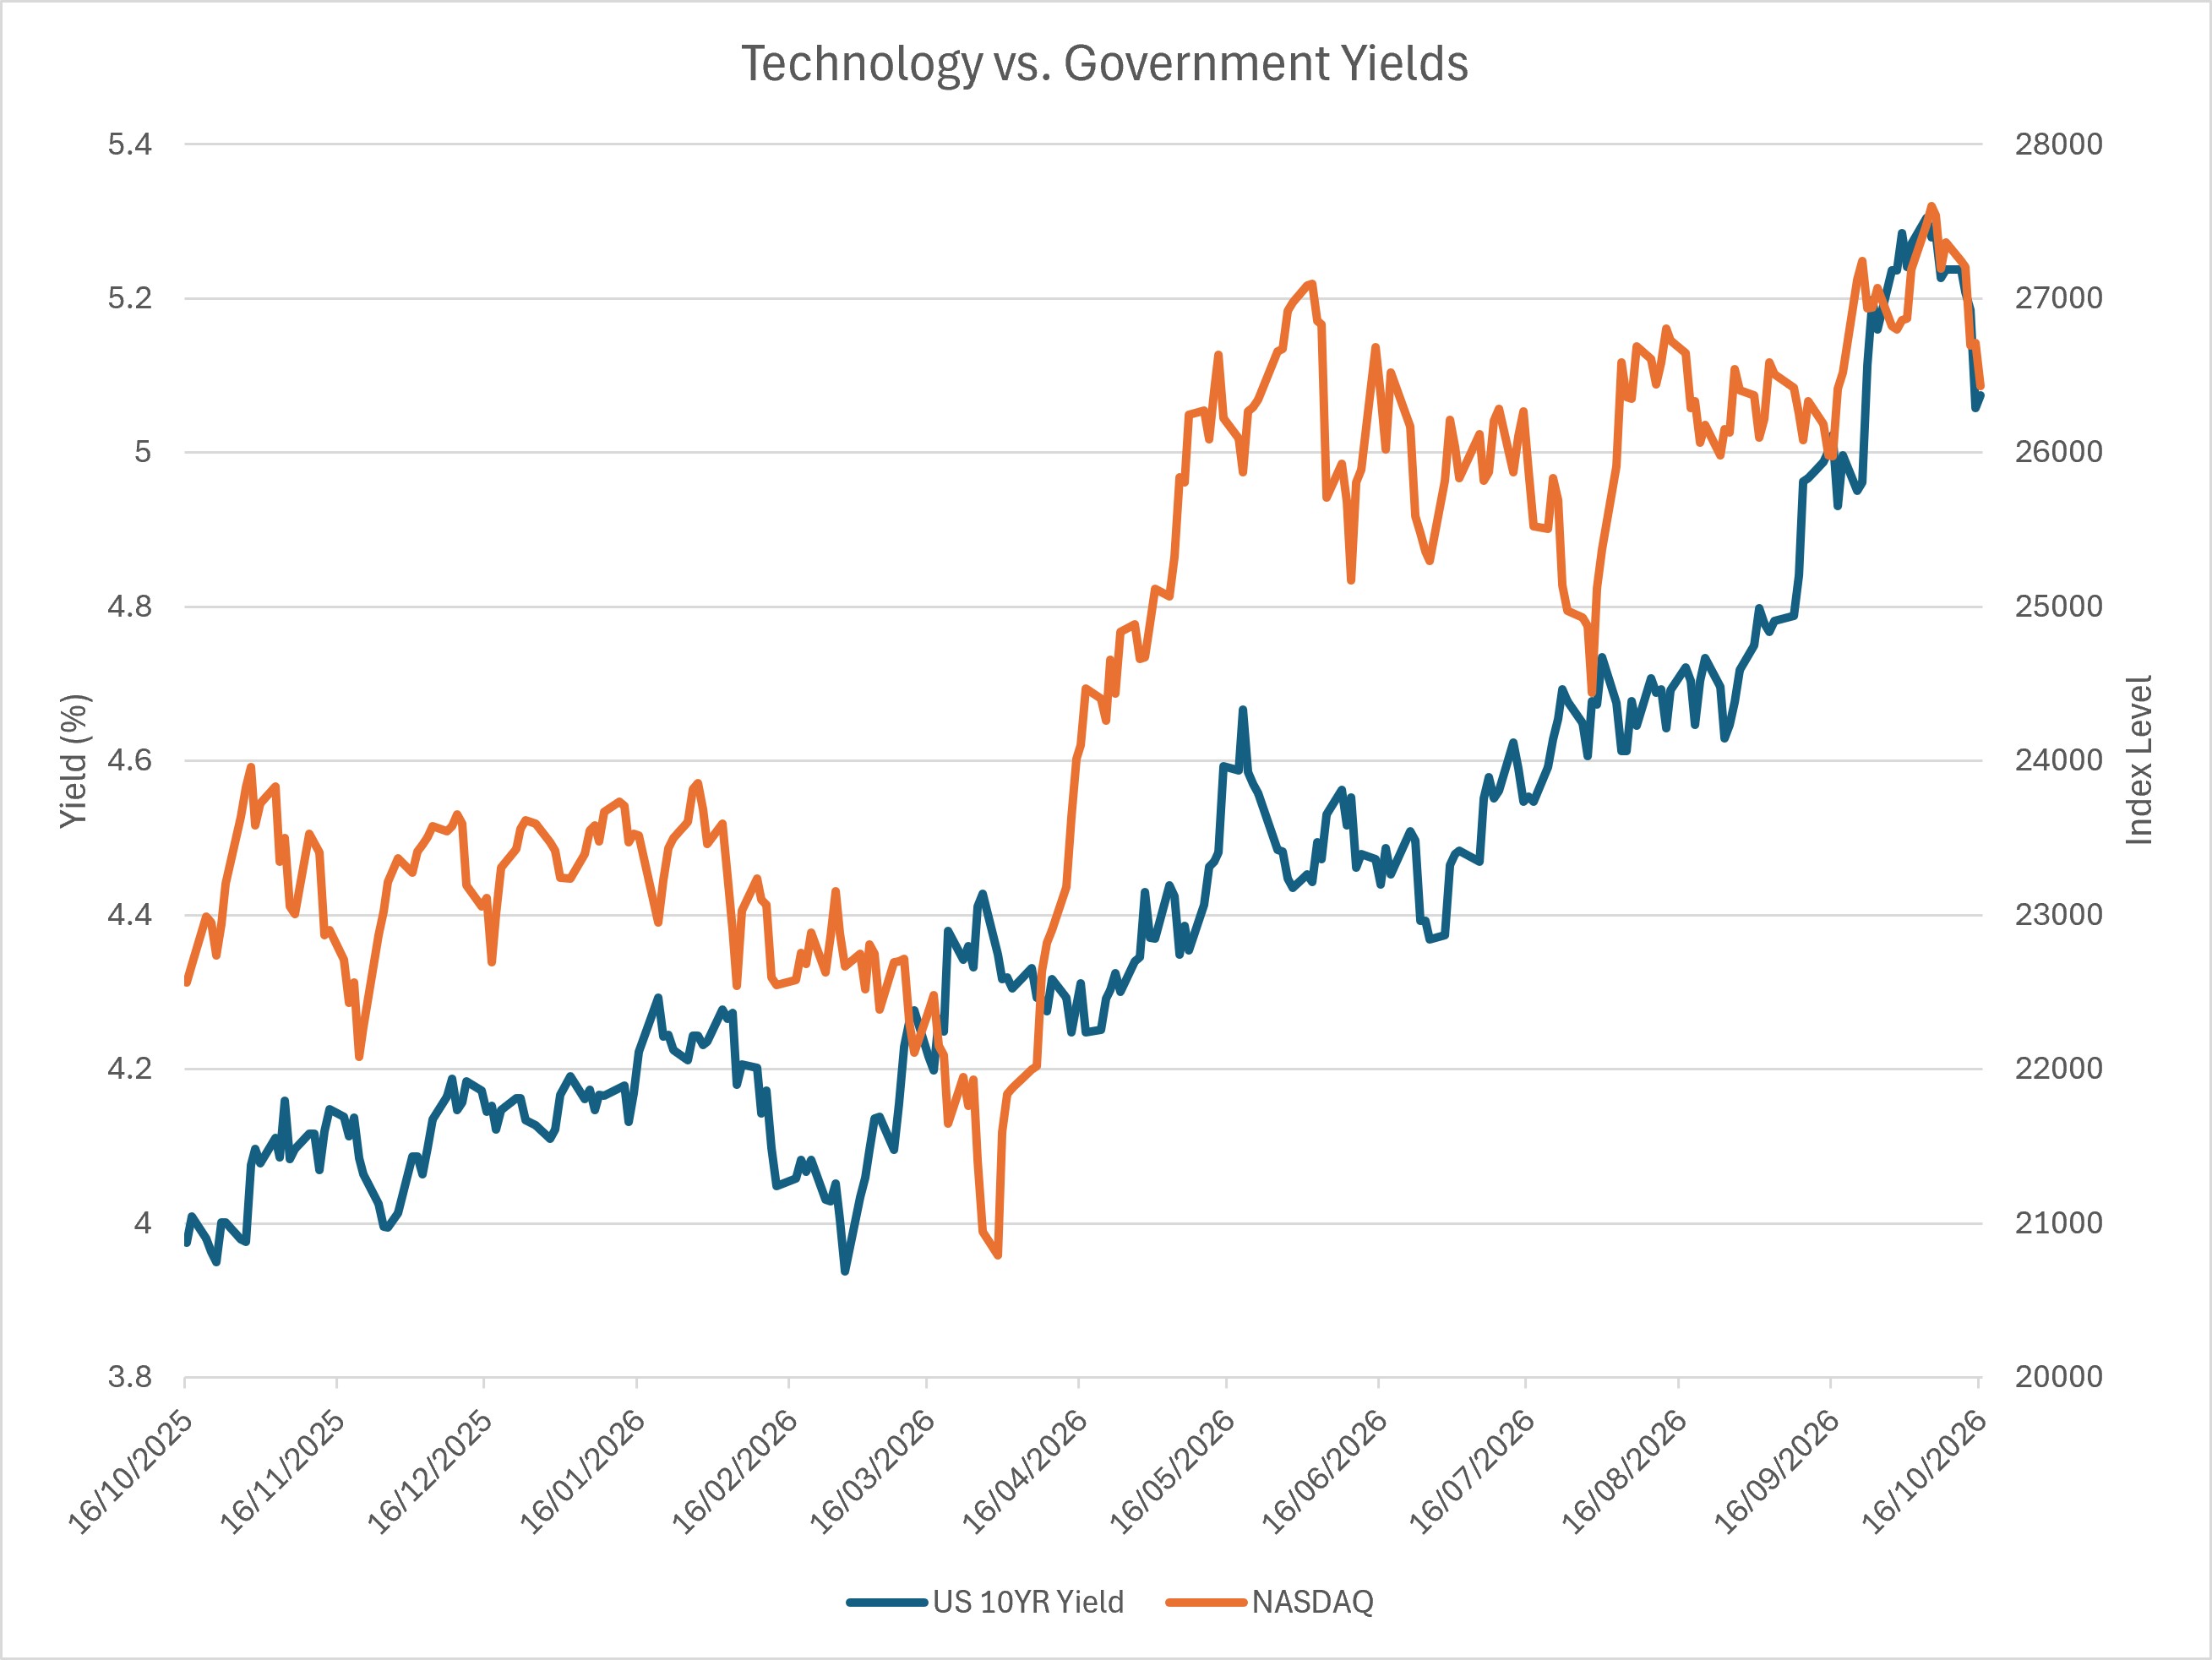
Source: Bloomberg, as of October 16, 2026. Muzinich views and opinions are subject to change. For illustrative purposes only, not to be construed as investment advice or an invitation to engage in any investment activity.
Past performance is not a reliable indicator of current or future results.
References to specific companies is for illustrative purposes only and does not reflect the holdings of any specific past or current portfolio or account.
This material is not intended to be relied upon as a forecast, research, or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or to adopt any investment strategy. The opinions expressed by Muzinich & Co. are as of October 16, 2026, and may change without notice. All data figures are from Bloomberg, as of October 16, 2026, unless otherwise stated.
References
[1] UBS China Economic Perspectives, “China and the EU released a joint statement after two days of negotiations in Beijing,” October 9, 2026
[2] Bloomberg, “China React: Supply-Led Reflation Risks Less Demand Stimulus,” October 13, 2026
[3] Bloomberg, “UK Unexpectedly Grows in August After Manufacturing Surge,” October 15, 2026
[4] Bloomberg, “IMF’s Tenreyro Tells UK to ‚Stay the Course’ on Fiscal Plans,” October 12, 2026
[5] Bloomberg, as of October 16, 2026
[6] Bloomberg, “US React: Hot Core CPI Masks a Decrease in Inflation Breadth,” October 16, 2026
[7] US Bureau of Labor Statistics, “Producer Price Indexes – September 2026,” October 15, 2026
[8] Bloomberg, “US Retail Sales Rise More Than Expected on Gasoline Receipts,” October 15, 2026
[9] Yahoo!Finance, “Selloff in CoreWeave stock is a buying opportunity: Deutsche Bank,” October 15, 2026
--------
Important information
Muzinich & Co., “Muzinich” and/or the “Firm” referenced herein is defined as Muzinich & Co. Inc. and its affiliates. This material has been produced for information purposes only and as such the views contained herein are not to be taken as investment advice. Opinions are as of date of publication and are subject to change without reference or notification to you. Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy. The value of investments and the income from them may fall as well as rise and is not guaranteed and investors may not get back the full amount invested. Rates of exchange may cause the value of investments to rise or fall. Emerging Markets may be more risky than more developed markets for a variety of reasons, including but not limited to, increased political, social and economic instability, heightened pricing volatility and reduced market liquidity. Any research in this document has been obtained and may have been acted on by Muzinich for its own purpose. The results of such research are being made available for information purposes and no assurances are made as to their accuracy. Opinions and statements of financial market trends that are based on market conditions constitute our judgment and this judgment may prove to be wrong. The views and opinions expressed should not be construed as an offer to buy or sell or invitation to engage in any investment activity, they are for information purposes only. Any forward-looking information or statements expressed in the above may prove to be incorrect. In light of the significant uncertainties inherent in the forward-looking statements included herein, the inclusion of such information should not be regarded as a representation that the objectives and plans discussed herein will be achieved. Muzinich gives no undertaking that it shall update any of the information, data and opinions contained in the above.
United States: This material is for Institutional Investor use only – not for retail distribution. Muzinich & Co., Inc. is a registered investment adviser with the Securities and Exchange Commission (SEC). Muzinich & Co., Inc.’s being a Registered Investment Adviser with the SEC in no way shall imply a certain level of skill or training or any authorization or approval by the SEC.
United Arab Emirates (UAE): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the UAE. It is intended solely for Professional Investors and should not be relied upon by any other person. This material has not been reviewed or approved by the UAE Securities and Commodities Authority, the UAE Central Bank or any other relevant authority. Nothing contained herein constitutes investment, legal, tax or other professional advice. Recipients should make their own independent assessment where appropriate.
Abu Dhabi Global Market (ADGM): This information is provided for discussion and informational purposes only and does not constitute an offer or solicitation in the ADGM. It is intended solely for Professional Clients (as defined by the Financial Services Regulatory Authority) and should not be relied upon by any other person. This material has not been reviewed or approved by the Financial Services Regulatory Authority or any other relevant authority in the UAE.
Issued in the European Union by Muzinich & Co. (Ireland) Limited, which is authorized and regulated by the Central Bank of Ireland. Registered in Ireland, Company Registration No. 307511. Registered address: 32 Molesworth Street, Dublin 2, D02 Y512, Ireland. Issued in Switzerland by Muzinich & Co. (Switzerland) AG. Registered in Switzerland No. CHE-389.422.108. Registered address: Tödistrasse 5, 8002 Zurich, Switzerland. Issued in Singapore and Hong Kong by Muzinich & Co. (Singapore) Pte. Limited, which is licensed and regulated by the Monetary Authority of Singapore. Registered in Singapore No. 201624477K. Registered address: 6 Battery Road, #26-05, Singapore, 049909. Issued in all other jurisdictions (excluding the U.S.) by Muzinich & Co. Limited. which is authorized and regulated by the Financial Conduct Authority. Registered in England and Wales No. 3852444. Registered address: 8 Hanover Street, London W1S 1YQ, United Kingdom.
By clicking "Submit", I am (i) signing up to receive the Opinion Pieces from the "Opinions" page of the Muzinich & Co website, (ii) representing that the above information is true and accurate and (iii) agreeing to join the Muzinich & Co mailing list. I understand that Muzinich & Co will not add retail investors or individuals with personal email addresses to its mailing list and represent that I am not a retail investor. By providing my personal and professional information I am consenting to its use and disclosure in accordance with the Muzinich & Co. Privacy Policy. I understand that I may withdraw my consent and unsubscribe from receiving future communications by clicking "Unsubscribe" from the emails that are sent to me from Muzinich & Co.
Oct 12, 2026
Muzinich Weekly Market Comment: Inflation, Growth, or Sustainability
It was a quiet week, at least relative to the past five, during which investor fears climbed, prompted by a wholesale reassessment of expectations for the final quarter. At the epicenter was central bank tightening, with investors pushing out their projections for the peak in rates across the globe.
Oct 08, 2026
Muzinich Asset Allocation Group Monthly Update - October 2026
Please click to watch our latest Asset Allocation Group video update for the month of September 2026.
Oct 08, 2026
Corporate Credit Snapshot - October 2026
September offered fixed income investors little room to hide, and global credit delivered negative returns as both short- and long-term rates moved higher.